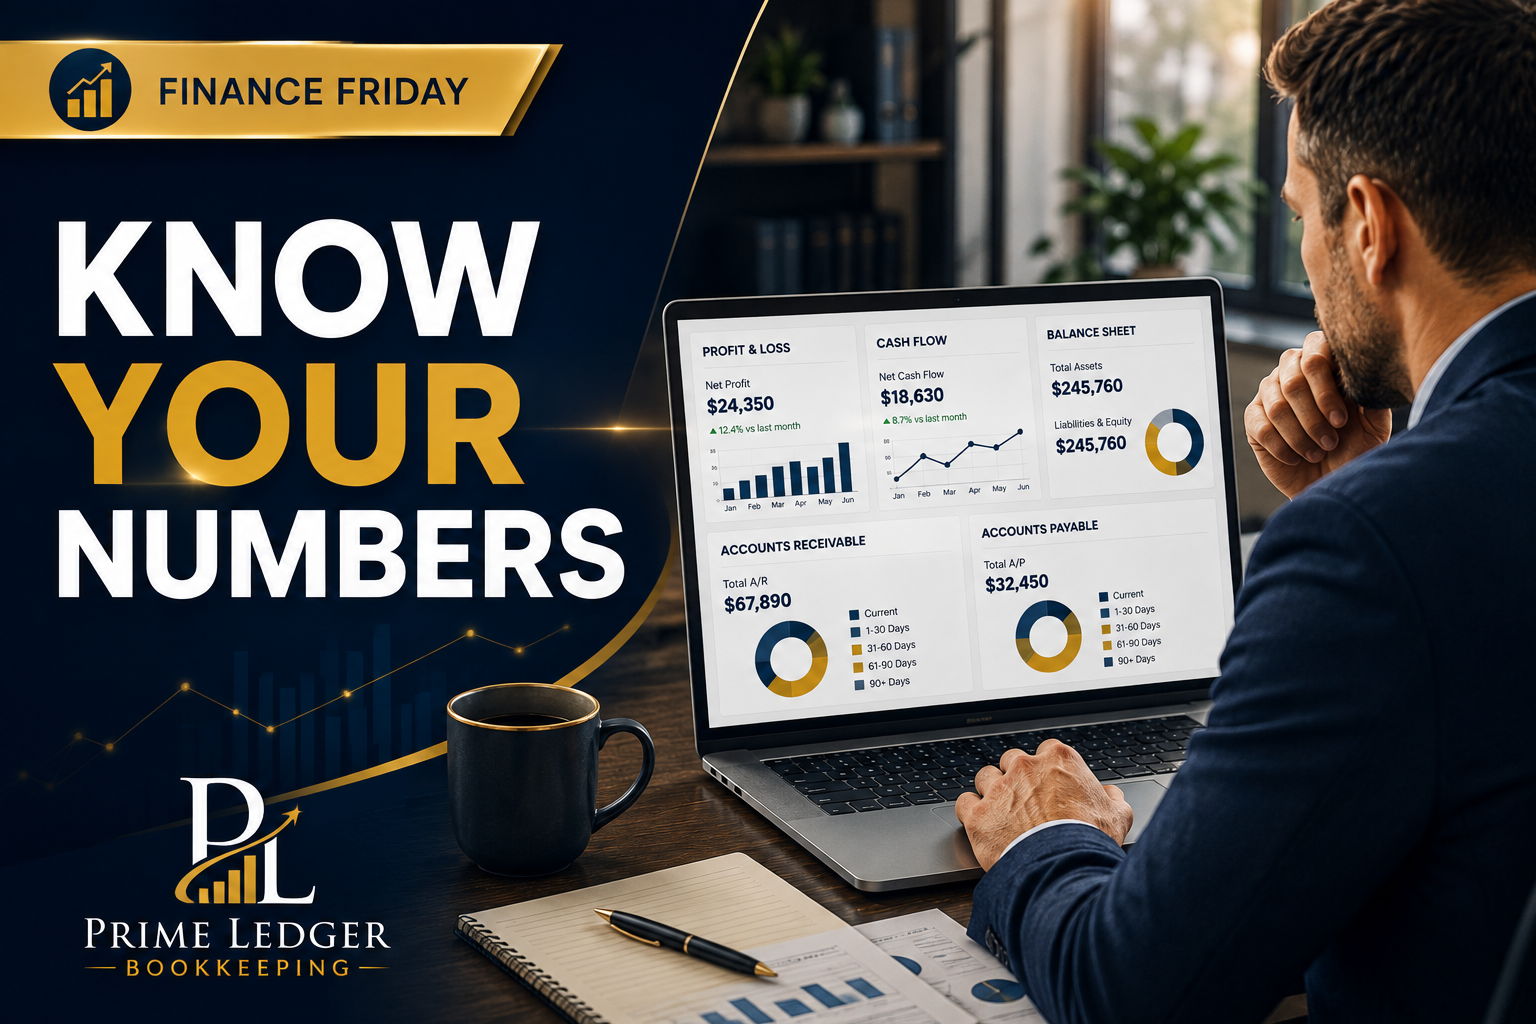
Your Business Numbers Should Tell You More Than What You Earned
As a business owner, you probably look at your bank account regularly.
You may also keep an eye on sales, invoices, and expenses.
But here’s a question worth asking:
Do you really know how your business is performing financially?
A healthy bank balance doesn’t necessarily mean your business is profitable.
Strong sales don’t necessarily mean you’re keeping enough money.
And having money in the bank today doesn’t necessarily mean you’ll have enough to cover next month’s payroll, vendor bills, or other obligations.
That’s where monthly financial reports become valuable.
These reports turn the transactions recorded in your books into information you can actually use.
They can help you understand:
- Whether your business is profitable
- What your business owns and owes
- Where your cash is coming from and going
- Which customers still owe you money
- Which bills and obligations are coming due
You don’t need to be an accountant to use financial reports.
You just need to understand what each report is telling you and why it matters.
In this guide, we’ll look at five important reports every small-business owner should understand and explain how they can help you make better decisions.
Table of Contents
- Why Monthly Financial Reports Matter
- 5 Monthly Financial Reports Every Owner Should Know
- How to Read These Reports Together
- How Often Should You Review Your Financial Reports?
- The Reports You Need Depend on Your Business
- What If Your Financial Reports Don’t Look Right?
- How Monthly Bookkeeping Makes Reporting Easier
- Why Financial Reports Matter for HVAC and Service Businesses
- How a Bookkeeper Can Help
- Key Takeaways
- Frequently Asked Questions
- Conclusion
Why Monthly Financial Reports Matter
Financial reports aren’t just documents you look at during tax season.
They’re management tools.
When you review your financial information regularly, you can start seeing patterns instead of simply reacting to what’s happening.
The IRS notes that good business records can help owners monitor the progress of their business and prepare accurate financial statements, including income statements and balance sheets.
You can learn more from the IRS guidance on keeping business records.
For example, you may discover that:
- Revenue is increasing but profit margins are declining
- One expense category is growing faster than expected
- Customers are taking longer to pay
- Vendor obligations are increasing
- Cash is tightening even though the business is profitable
These are things you want to know while you still have time to respond.
Waiting until the end of the year to review your numbers can mean missing opportunities to correct problems or take advantage of positive trends.
Monthly reporting gives you a more timely view of what’s happening in your business—and gives you information you can actually use to make decisions.
5 Monthly Financial Reports Every Owner Should Know
1. Profit & Loss Statement
What does it tell you?
Are we making money?
The Profit & Loss statement, often called the P&L, summarizes your business’s revenue and expenses over a specific period.
It generally shows:
- Revenue
- Cost of goods or services
- Gross profit
- Operating expenses
- Net profit or loss
For example, an HVAC business may generate strong sales during a busy month.
But after accounting for technician wages, materials, vehicle costs, insurance, advertising, and other expenses, the actual profit may be much lower than expected.
The P&L helps you see that difference.
What should you look for?
Don’t just look at the bottom-line profit.
Compare your results with previous months and ask:
- Is revenue increasing?
- Are expenses increasing faster than revenue?
- Are margins changing?
- Which expenses are unusually high?
- Is the business becoming more or less profitable?
The goal isn’t simply to know whether you made money.
It’s to understand why.
2. Balance Sheet
What does it tell you?
What does the business own, owe, and have invested in it?
While the P&L focuses on income and expenses over a period, the Balance Sheet gives you a snapshot of your financial position at a specific point in time.
It generally includes:
Assets
What the business owns or controls.
Examples include:
- Cash
- Accounts receivable
- Equipment
- Vehicles
- Other business assets
Liabilities
What the business owes.
Examples include:
- Vendor bills
- Loans
- Credit cards
- Other obligations
Equity
The owner’s financial interest in the business after liabilities are considered.
What should you look for?
Pay attention to significant changes.
For example:
- Is cash increasing or declining?
- Are customer receivables growing?
- Are liabilities increasing?
- Are loans being paid down?
- Are there unusual or unexplained balances?
The Balance Sheet can reveal things that aren’t obvious from the P&L alone.
3. Cash Flow Statement
What does it tell you?
Where is the cash coming from, and where is it going?
This is particularly important because profit and cash are not the same thing.
You can have a profitable month and still experience cash-flow pressure.
For example, imagine your HVAC business completes $50,000 of work in June.
You record the revenue.
But if several customers don’t pay until July or August, you may not actually have that $50,000 available in June.
Meanwhile, payroll, materials, fuel, rent, and vendor bills still need to be paid.
A cash flow report helps you understand how cash is moving through the business.
What should you look for?
Ask:
- Is the business generating enough operating cash?
- Are large amounts of cash tied up in receivables?
- Are loan payments affecting cash?
- Are there significant equipment purchases?
- Is cash consistently declining?
Understanding cash flow can help you avoid being caught off guard by a shortage of available cash.
4. Accounts Receivable Aging Report
What does it tell you?
Who owes you money—and how long have they owed it?
If you invoice customers, this report can be extremely useful.
An A/R aging report typically organizes outstanding invoices based on how long they’ve been unpaid.
For example:
- Current
- 1–30 days
- 31–60 days
- 61–90 days
- 90+ days
Imagine you have $80,000 in outstanding customer invoices.
That number alone doesn’t tell you everything.
If $70,000 is current and only $10,000 is significantly overdue, the situation is very different from having $50,000 sitting unpaid for more than 90 days.
What should you look for?
Pay particular attention to older balances.
Ask:
- Which customers are overdue?
- How long have they been outstanding?
- Are there customers who consistently pay late?
- Are there invoices that need follow-up?
- Are there balances that may need investigation?
Getting paid for the work you’ve already completed is an important part of managing cash flow.
5. Accounts Payable Aging Report
What does it tell you?
What does your business owe—and when is it due?
An A/P aging report helps you understand outstanding vendor obligations.
It can show:
- Current bills
- Upcoming payments
- Past-due bills
- Vendor balances
- Aging of outstanding obligations
For a service business, this might include suppliers for materials, equipment vendors, software providers, and other business expenses.
What should you look for?
Ask:
- What bills are due soon?
- Are any bills overdue?
- Are vendor balances unusually high?
- Are there duplicate or old bills?
- Do you have enough cash to cover upcoming obligations?
Knowing what you owe can help you plan rather than react.
How to Read These Reports Together
One of the biggest mistakes business owners make is looking at each report in isolation.
The real value comes from connecting the information.
Imagine your P&L shows a healthy profit.
That sounds good.
But then you look at your Balance Sheet and see that accounts receivable has increased significantly.
Your A/R aging report shows that several large invoices are more than 60 days old.
Your cash flow report shows that available cash is tightening.
Now you have a much clearer picture.
The business may be profitable—but cash is being tied up in unpaid customer invoices.
That’s the kind of insight that individual reports may not provide on their own.
Think of the reports as pieces of the same financial picture:
P&L → Profitability
Balance Sheet → Financial position
Cash Flow → Movement of cash
A/R Aging → Money customers owe you
A/P Aging → Money you owe others
Together, they can give you a much more complete view of your business.
How Often Should You Review Your Financial Reports?
For many small businesses, monthly is a practical starting point.
Monthly reporting gives you enough information to identify trends without overwhelming you with daily fluctuations.
However, some businesses may benefit from reviewing certain information more frequently.
For example:
- Cash position may need weekly monitoring
- A/R may need frequent follow-up
- High-volume businesses may review sales more often
- Large businesses may use daily or weekly dashboards
The important thing is consistency.
A report isn’t very useful if you generate it once and never look at it again.
The Reports You Need Depend on Your Business
The five reports discussed here provide a strong foundation for many small businesses.
But your business may need additional information.
Depending on your operations, you might also benefit from:
- Sales by customer
- Sales by service
- Job profitability
- Budget vs. actual
- Expense analysis
- Inventory reports
- Technician or department performance
- Customer concentration reports
For example, an HVAC business may want to understand whether certain service types or jobs are producing stronger margins.
The goal isn’t to create dozens of reports.
The goal is to have the right information for the decisions you need to make.
What If Your Financial Reports Don’t Look Right?
Sometimes the problem isn’t the report.
It’s the bookkeeping behind it.
If your financial reports contain unusual numbers, unexplained balances, or results that don’t match what you know about the business, don’t simply ignore them.
Start by asking:
- Are all transactions recorded?
- Are bank accounts reconciled?
- Are credit cards reconciled?
- Are transactions categorized correctly?
- Is A/R current?
- Is A/P current?
- Are there duplicate transactions?
- Are there old or unexplained balances?
Reliable reports depend on reliable underlying records.
That’s one reason we emphasize the importance of accurate books.
How Monthly Bookkeeping Makes Reporting Easier
Financial reports don’t appear out of nowhere.
They depend on the bookkeeping process behind them.
A consistent monthly bookkeeping process can include:
- Recording transactions
- Categorizing income and expenses
- Reconciling bank accounts
- Reconciling credit cards
- Reviewing accounts receivable
- Reviewing accounts payable
- Investigating unusual transactions
- Reviewing financial reports
When these tasks are completed consistently, your monthly financial reports become much more useful.
Instead of spending hours trying to reconstruct what happened, you can focus on understanding the numbers and deciding what to do next.
Why Financial Reports Matter for HVAC and Service Businesses
For HVAC and service-based businesses, financial reports can provide insight into areas that directly affect profitability and cash flow.
Profit & Loss
Are labor and material costs growing faster than revenue?
Balance Sheet
How much cash, equipment, and receivables does the business have?
Cash Flow
Can you cover payroll, vendors, vehicle expenses, and other upcoming obligations?
A/R Aging
Are customers paying promptly after services are completed?
A/P Aging
Are vendor obligations increasing?
These reports can help answer practical questions such as:
Can we afford another technician?
Can we purchase another service vehicle?
Are our margins improving?
Do we have enough cash for a slower season?
Are customers taking too long to pay?
Those aren’t just accounting questions.
They’re business decisions.
How a Bookkeeper Can Help
You don’t need to become an accountant to understand your business finances.
A professional bookkeeper can help maintain the records that produce your monthly financial reports and help ensure those reports are based on organized, current information.
For HVAC and service-based businesses, monthly bookkeeping support may include:
- Transaction categorization
- Bank reconciliation
- Credit card reconciliation
- Accounts receivable
- Accounts payable
- Monthly financial reporting
The goal isn’t to overwhelm you with accounting terminology.
It’s to give you clear financial information you can actually use.
At Prime Ledger Bookkeeping, we help HVAC and service-based businesses maintain organized books and monthly financial reports so owners can spend less time worrying about their numbers and more time running their businesses.
Key Takeaways
Monthly financial reports aren’t just for tax preparation. They’re tools for running your business.
The five reports every owner should understand are:
✅ Profit & Loss — shows profitability
✅ Balance Sheet — shows financial position
✅ Cash Flow Statement — shows how cash moves
✅ A/R Aging — shows who owes you and how overdue those balances are
✅ A/P Aging — shows what you owe and what’s coming due
But don’t stop at simply generating the reports.
Review them. Compare them. Ask questions. Look for changes.
The real value comes from using the information to make better decisions.
Frequently Asked Questions
What financial reports should a small business review monthly?
Many small businesses can benefit from reviewing the Profit & Loss, Balance Sheet, Cash Flow Statement, Accounts Receivable Aging, and Accounts Payable Aging reports each month. The exact reports needed depend on the business.
What is the most important financial report for a small business?
There isn’t one report that is most important for every business. The Profit & Loss is useful for understanding profitability, while the Balance Sheet, Cash Flow, A/R, and A/P reports provide other important parts of the financial picture.
How often should a business review financial reports?
Many small businesses should review their financial reports monthly. Certain information, such as cash and accounts receivable, may need to be monitored more frequently depending on the business.
Why is a Profit & Loss statement important?
A Profit & Loss statement shows revenue, expenses, and resulting profit or loss over a specific period. It can help business owners understand whether the business is profitable and identify changes in income and expenses.
Why is the Balance Sheet important?
The Balance Sheet provides a snapshot of what a business owns, what it owes, and its equity at a specific point in time. It can reveal financial changes that may not be obvious from the Profit & Loss statement.
Do small businesses need a Cash Flow Statement?
Not every small business needs a formal Cash Flow Statement every month, but understanding cash inflows and outflows is important for virtually every business. Cash flow information can help owners anticipate shortages and plan for upcoming obligations.
What is an A/R aging report?
An Accounts Receivable Aging report shows outstanding customer invoices and categorizes them based on how long they have been unpaid. It can help business owners identify overdue invoices that may require follow-up.
What is an A/P aging report?
An Accounts Payable Aging report shows outstanding vendor bills and organizes them according to how long they have been unpaid. It helps business owners understand upcoming and overdue obligations.
Can a bookkeeper prepare monthly financial reports?
Yes. A bookkeeper can maintain the underlying financial records, reconcile accounts, review A/R and A/P, and prepare or provide monthly financial reports based on the bookkeeping system.
Conclusion
You don’t need to be an accountant to understand your business finances.
But you do need reliable information.
Monthly financial reports can help you move beyond simply looking at your bank balance or total sales and start understanding what’s actually happening inside your business.
Your Profit & Loss can show whether you’re profitable.
Your Balance Sheet can show what you own and owe.
Your cash flow information can show how money is moving.
Your A/R report can show who still owes you.
And your A/P report can show what you need to pay.
Together, these reports give you a clearer financial picture—and that picture can help you make better decisions.
If you’re not currently receiving and reviewing these reports each month, it may be time to establish a more consistent bookkeeping process.
At Prime Ledger Bookkeeping, we help HVAC and service-based businesses maintain accurate books and receive useful monthly financial reports without having to manage the bookkeeping themselves.
Your numbers should do more than record what happened. They should help you decide what to do next.
Accurate Books. Clear Decisions. Peace of Mind.
Related Articles
Why Accurate Books Matter
Learn why reliable and current financial records are essential for making better business decisions.
What Does a Bookkeeper Do? A Complete Guide for Small Business Owners
Understand what a bookkeeper does and how ongoing bookkeeping supports your business.
Still Using Spreadsheets? Here’s the Risk.
Learn the warning signs that your spreadsheet-based bookkeeping system may no longer be keeping up with your business.
Let’s Get Your Books Back on Track
If your financial records aren’t accurate or current, learn how bookkeeping cleanup can help.
5 Signs It’s Time to Hire a Bookkeeper
Not sure whether professional bookkeeping support makes sense for your business? Start here.
Leave a Reply