Accurate Books. Clear Decisions. Peace of Mind.

Richardson, TX 75081

Tag: Financial Management

  • Cash Flow vs. Profit: Why Your Business Can Be Profitable and Still Run Out of Cash

    Cash Flow vs. Profit: Why Your Business Can Be Profitable and Still Run Out of Cash

    Your business works hard. Make sure your cash flow works, too.

    This Labor Day, we’re celebrating the people behind America’s small businesses—the owners and workers who put in the hours, serve customers, solve problems, and keep businesses moving.

    But there’s another side to all that hard work: knowing whether the business is actually generating enough cash to support it.

    Because here’s something many business owners discover the hard way:

    A profitable business can still run out of cash.

    If you’ve ever looked at your profit and loss statement and thought, “I made money this month, so why does my bank account feel so low?” you’re not alone.

    The answer often comes down to understanding cash flow vs. profit.

    These two numbers tell you different parts of your business’s financial story. Knowing the difference can help you spot cash shortages earlier, plan for upcoming expenses, and make better decisions about your business.


    Table of Contents

    1. Key Takeaways
    2. What Is Profit?
    3. What Is Cash Flow?
    4. Cash Flow vs. Profit: What’s the Difference?
    5. 7 Reasons a Profitable Business Can Still Run Out of Cash
    6. An HVAC Example: Profitable on Paper, Short on Cash
    7. What Small-Business Owners Should Watch
    8. How Good Bookkeeping Helps You See the Full Picture
    9. Conclusion
    10. Frequently Asked Questions
    11. Need Help Understanding Your Numbers?

    Key Takeaways

    • Profit and cash flow are not the same thing.
    • Profit shows whether your business earned more than it spent during a particular period.
    • Cash flow tracks money actually moving into and out of the business.
    • A business can report a profit while having little cash available.
    • Unpaid invoices, equipment purchases, loan payments, owner withdrawals, and timing differences can all affect cash.
    • Reviewing your P&L alone isn’t enough to understand your business’s financial position.
    • Accurate bookkeeping gives you better information for monitoring both profitability and cash availability.

    What Is Profit?

    Profit is essentially what remains after your business’s revenue is reduced by its expenses.

    For example:

    Revenue: $20,000
    Expenses: $14,000
    Profit: $6,000

    Your profit and loss statement, commonly called a P&L, helps you see whether the business generated a profit or loss during a particular period.

    The IRS describes an income statement as showing the income and expenses of a business for a given period. Accurate records are important for preparing reliable financial statements and monitoring the progress of a business. (IRS)

    Profit is important because it helps answer a fundamental question:

    Is the business financially profitable based on its revenues and expenses?

    But profit doesn’t necessarily tell you how much money is available in your bank account today.

    That’s where cash flow comes in.


    What Is Cash Flow?

    Cash flow is about the movement of money into and out of your business.

    Cash inflows can include:

    • Customer payments
    • Deposits
    • Loan proceeds
    • Owner contributions
    • Other cash received by the business

    Cash outflows can include:

    • Payroll
    • Vendor payments
    • Rent
    • Utilities
    • Insurance
    • Equipment purchases
    • Loan payments
    • Owner withdrawals

    The timing of those inflows and outflows matters.

    Imagine you invoice a customer $10,000 today but won’t receive payment for 30 days.

    You may have earned revenue, but you don’t yet have that $10,000 available in your bank account.

    This is one reason understanding cash flow vs. profit is so important for small-business owners.

    The SBA notes that businesses may use either cash or accrual accounting, and under accrual accounting a sale can be recorded when it occurs even if payment comes later. (Small Business Administration)


    Cash Flow vs. Profit: What’s the Difference?

    Here’s a simple way to think about it:

    ProfitCash Flow
    Measures revenue and expensesMeasures cash coming in and going out
    Appears on the profit and loss statementCan be analyzed through cash-flow reporting and cash activity
    Can include revenue that hasn’t been collected yet under accrual accountingFocuses on actual movement of cash
    Helps measure profitabilityHelps you understand liquidity and cash availability
    Answers: “Did the business make money?”Answers: “Do we have enough cash to meet our obligations?”

    Neither one tells the entire story by itself.

    Profitability matters for the long-term health of the business. Cash availability matters for keeping the business operating day to day.

    You need to understand both.


    7 Reasons a Profitable Business Can Still Run Out of Cash

    Understanding cash flow vs. profit becomes much easier when you look at what can cause the two numbers to move in different directions.

    1. Your Customers Haven’t Paid Their Invoices Yet

    This is especially common for service businesses.

    Suppose your HVAC company completes $15,000 of work in August and invoices the customers.

    If you use accrual accounting, that revenue may be reflected in August even though your customers don’t pay until September.

    Your August P&L could therefore show strong revenue and a healthy profit.

    But your bank account doesn’t have that $15,000 yet.

    Revenue isn’t the same thing as collected cash.

    This is why accounts receivable deserves regular attention.

    2. You Made a Large Equipment Purchase

    Let’s say your business purchases a $12,000 piece of equipment.

    Your bank account immediately feels the $12,000 cash outflow.

    But the way that purchase affects your financial statements can be different from the timing of the cash leaving your account, particularly when the equipment is recorded as an asset and depreciated over time.

    This can create a situation where:

    Cash decreases significantly while the expense recognized on the P&L is different.

    Large purchases therefore deserve special attention when you’re reviewing cash flow.

    3. You’re Paying Down Business Loans

    Loan payments can also create confusion.

    A loan payment generally contains both:

    • Principal
    • Interest

    The cash leaves your bank account for the entire payment.

    But principal repayment isn’t simply another operating expense on your P&L.

    That means your bank balance can decline even though your reported profit doesn’t decline by the same amount.

    This is another important reason to look beyond the P&L.

    4. You’re Taking Money Out of the Business

    Owner draws or distributions can reduce the amount of cash available to the business without necessarily appearing as an operating expense on the P&L.

    For example, suppose your business earns $8,000 in profit.

    You then transfer $5,000 to your personal account.

    Your business may still show $8,000 of profit, but there is now $5,000 less cash available to the business.

    That’s why business owners need to distinguish between:

    “The business earned money.”

    and

    “The business currently has money available.”

    They’re not necessarily the same statement.

    5. Your Expenses Are Due Before Customer Payments Arrive

    Cash-flow problems are often about timing.

    Imagine:

    • Customer invoices are due in 30 days.
    • Your supplier expects payment in 15 days.
    • Payroll is due Friday.
    • Your insurance payment is due next week.

    Your business may be profitable overall, but the timing of cash coming in doesn’t line up with the timing of cash going out.

    That’s a cash-flow problem.

    6. You’re Growing Faster Than Your Cash Can Support

    Growth sounds great—and it can be.

    But growth can require cash.

    You may need to:

    • Hire additional technicians
    • Purchase inventory or equipment
    • Increase advertising
    • Purchase vehicles
    • Carry larger receivables
    • Pay vendors before customers pay you

    So a growing business can actually experience more pressure on cash, even while revenue and profit are increasing.

    Growth doesn’t automatically mean cash is plentiful.

    7. You’re Looking Only at Your Bank Balance

    The opposite problem can happen too.

    A healthy bank balance doesn’t automatically mean your business is profitable.

    Your bank account might contain:

    • A recently received customer payment
    • Loan proceeds
    • Owner contributions
    • Money set aside for taxes
    • Cash needed for upcoming bills

    Looking only at the bank balance can therefore give you an incomplete picture.

    The bank account tells you what’s there. Your financial reports help explain why it’s there and what your business is actually earning.


    An HVAC Example: Profitable on Paper, Short on Cash

    Let’s make this practical.

    Imagine ABC Heating & Air completes several jobs during August.

    August activity

    Customer invoices: $25,000
    Business expenses: $17,000
    Profit: $8,000

    At first glance, that looks pretty good.

    But there’s a catch.

    Of the $25,000 invoiced:

    $15,000 hasn’t been collected yet.

    Meanwhile, the company has already paid technicians, suppliers, fuel, insurance, and other operating expenses.

    The P&L may show an $8,000 profit, while the company’s available cash is much lower than the owner expected.

    The owner might ask:

    “Where did my profit go?”

    The answer isn’t necessarily that the profit disappeared.

    Part of the business’s earnings may still be sitting in accounts receivable, waiting for customers to pay.

    And other cash movements—such as equipment purchases, loan principal payments, or owner withdrawals—may have reduced the bank balance without reducing profit in the same way.

    This is exactly why looking at cash flow vs. profit gives you a more complete financial picture.


    What Small-Business Owners Should Watch

    You don’t have to become an accountant to keep an eye on your business finances.

    Start by regularly reviewing these areas.

    1. Accounts Receivable

    How much money do customers currently owe you?

    More importantly:

    How much is overdue?

    A growing accounts-receivable balance can eventually create a cash problem.

    2. Accounts Payable

    What bills are coming due?

    Knowing what you owe—and when you owe it—helps you anticipate cash needs.

    3. Profit and Loss Statement

    Look at:

    • Revenue
    • Cost of goods sold, when applicable
    • Operating expenses
    • Net profit

    Don’t just look at whether you’re profitable. Look for trends.

    4. Bank Balance

    Know how much cash is actually available.

    But don’t treat the bank balance as your complete financial report.

    5. Upcoming Large Expenses

    Look ahead for:

    • Equipment purchases
    • Insurance renewals
    • Tax payments
    • Loan payments
    • Vehicle expenses
    • Payroll increases
    • Seasonal expenses

    6. Owner Withdrawals

    Make sure you understand how much money is leaving the business for personal use.

    7. Cash Reserves

    Ask yourself:

    If customer payments were delayed for 30 days, could my business still cover its essential expenses?

    That’s a much more useful question than simply asking whether the bank account looks healthy today.


    How Good Bookkeeping Helps You See the Full Picture

    Understanding cash flow vs. profit starts with having reliable financial records.

    If transactions are missing, incorrectly categorized, or unreconciled, your financial reports can become difficult to trust.

    The IRS explains that good business records help owners monitor business progress and prepare accurate financial statements. It also notes that supporting documents such as invoices, receipts, deposit slips, and paid bills provide information needed to record business transactions. (IRS)

    For small-business owners, that means bookkeeping isn’t just about categorizing transactions.

    It’s about creating financial information you can actually use.

    A good bookkeeping process can help you:

    • Keep revenue and expenses organized
    • Track accounts receivable
    • Monitor accounts payable
    • Reconcile bank accounts
    • Identify unusual transactions
    • Review financial reports
    • Spot trends
    • Prepare for tax filing
    • Make better business decisions

    The SBA similarly recommends maintaining proper bookkeeping and having a basic understanding of business finances, including accounting methods, accounts receivable, accounts payable, available cash, and bank reconciliation. (Small Business Administration)

    IRS: Why Should I Keep Records?

    SBA: Manage Your Business Finances


    Conclusion

    Your Business Works Hard. Your Numbers Should Work Hard, Too.

    This Labor Day, while we’re celebrating the people who make small businesses work, it’s worth remembering that hard work alone doesn’t tell you whether your business is financially healthy.

    You need visibility into the numbers.

    Profit tells you whether your business is earning more than it spends.

    Cash flow tells you how money is actually moving through the business.

    And you need both perspectives.

    A business can be profitable and still experience a cash shortage. It can also have plenty of money in the bank and still be losing money.

    That’s why understanding cash flow vs. profit matters.

    When your books are accurate and your financial reports are up to date, you can see what’s happening before a small cash-flow issue becomes a major problem.

    You put in the labor. Let your numbers tell you whether that labor is paying off.


    Frequently Asked Questions

    Is cash flow the same as profit?

    No. Profit measures the difference between revenue and expenses over a period. Cash flow focuses on money moving into and out of the business. The two can differ because of payment timing, financing, asset purchases, owner transactions, and other factors.

    Can a business be profitable but have negative cash flow?

    Yes. A business can report a profit while experiencing negative cash flow during a period. For example, customers may not have paid their invoices yet while the business has already paid employees, suppliers, or other expenses.

    Which is more important: profit or cash flow?

    Neither should be viewed in isolation. Profit helps you understand whether the business model is generating earnings, while cash flow helps you understand whether the business has enough cash to meet its obligations.

    Why doesn’t my bank balance match my profit?

    Your bank balance reflects cash activity, while profit reflects revenue and expenses according to your accounting method. Loan principal payments, owner withdrawals, unpaid invoices, equipment purchases, and other transactions can cause the two numbers to differ.

    How often should a small business review cash flow?

    At minimum, business owners should regularly review their cash position and upcoming inflows and outflows. Businesses with tight margins, seasonal revenue, rapid growth, or significant accounts receivable may benefit from reviewing cash flow more frequently.


    Need Help Understanding Your Numbers?

    You shouldn’t have to guess whether your business is making money—or wonder where the cash went.

    Prime Ledger Bookkeeping helps small-business owners keep their books organized, understand their financial reports, and make decisions with greater confidence.

    From monthly bookkeeping and reconciliations to clear financial reporting, we’re here to help you get a better picture of your business finances.

    Accurate Books. Clear Decisions. Peace of Mind.

    Ready to understand your numbers better?

    Schedule a Free Consultation with Prime Ledger Bookkeeping.

    Related Articles

    Why Your Bank Balance Doesn’t Match Your Books

    Bookkeeping vs. Accounting: Explained

    Cash vs. Accrual Accounting: What’s the Difference?

    Let’s Get Your Books Back on Track

  • The Monthly Financial Reports Every Owner Needs

    The Monthly Financial Reports Every Owner Needs

    Your Business Numbers Should Tell You More Than What You Earned

    As a business owner, you probably look at your bank account regularly.

    You may also keep an eye on sales, invoices, and expenses.

    But here’s a question worth asking:

    Do you really know how your business is performing financially?

    A healthy bank balance doesn’t necessarily mean your business is profitable.

    Strong sales don’t necessarily mean you’re keeping enough money.

    And having money in the bank today doesn’t necessarily mean you’ll have enough to cover next month’s payroll, vendor bills, or other obligations.

    That’s where monthly financial reports become valuable.

    These reports turn the transactions recorded in your books into information you can actually use.

    They can help you understand:

    • Whether your business is profitable
    • What your business owns and owes
    • Where your cash is coming from and going
    • Which customers still owe you money
    • Which bills and obligations are coming due

    You don’t need to be an accountant to use financial reports.

    You just need to understand what each report is telling you and why it matters.

    In this guide, we’ll look at five important reports every small-business owner should understand and explain how they can help you make better decisions.


    Table of Contents

    1. Why Monthly Financial Reports Matter
    2. 5 Monthly Financial Reports Every Owner Should Know
    3. How to Read These Reports Together
    4. How Often Should You Review Your Financial Reports?
    5. The Reports You Need Depend on Your Business
    6. What If Your Financial Reports Don’t Look Right?
    7. How Monthly Bookkeeping Makes Reporting Easier
    8. Why Financial Reports Matter for HVAC and Service Businesses
    9. How a Bookkeeper Can Help
    10. Key Takeaways
    11. Frequently Asked Questions
    12. Conclusion

    Why Monthly Financial Reports Matter

    Financial reports aren’t just documents you look at during tax season.

    They’re management tools.

    When you review your financial information regularly, you can start seeing patterns instead of simply reacting to what’s happening.

    The IRS notes that good business records can help owners monitor the progress of their business and prepare accurate financial statements, including income statements and balance sheets.

    You can learn more from the IRS guidance on keeping business records.

    For example, you may discover that:

    • Revenue is increasing but profit margins are declining
    • One expense category is growing faster than expected
    • Customers are taking longer to pay
    • Vendor obligations are increasing
    • Cash is tightening even though the business is profitable

    These are things you want to know while you still have time to respond.

    Waiting until the end of the year to review your numbers can mean missing opportunities to correct problems or take advantage of positive trends.

    Monthly reporting gives you a more timely view of what’s happening in your business—and gives you information you can actually use to make decisions.


    5 Monthly Financial Reports Every Owner Should Know

    1. Profit & Loss Statement

    What does it tell you?

    Are we making money?

    The Profit & Loss statement, often called the P&L, summarizes your business’s revenue and expenses over a specific period.

    It generally shows:

    • Revenue
    • Cost of goods or services
    • Gross profit
    • Operating expenses
    • Net profit or loss

    For example, an HVAC business may generate strong sales during a busy month.

    But after accounting for technician wages, materials, vehicle costs, insurance, advertising, and other expenses, the actual profit may be much lower than expected.

    The P&L helps you see that difference.

    What should you look for?

    Don’t just look at the bottom-line profit.

    Compare your results with previous months and ask:

    • Is revenue increasing?
    • Are expenses increasing faster than revenue?
    • Are margins changing?
    • Which expenses are unusually high?
    • Is the business becoming more or less profitable?

    The goal isn’t simply to know whether you made money.

    It’s to understand why.

    2. Balance Sheet

    What does it tell you?

    What does the business own, owe, and have invested in it?

    While the P&L focuses on income and expenses over a period, the Balance Sheet gives you a snapshot of your financial position at a specific point in time.

    It generally includes:

    Assets

    What the business owns or controls.

    Examples include:

    • Cash
    • Accounts receivable
    • Equipment
    • Vehicles
    • Other business assets

    Liabilities

    What the business owes.

    Examples include:

    • Vendor bills
    • Loans
    • Credit cards
    • Other obligations

    Equity

    The owner’s financial interest in the business after liabilities are considered.

    What should you look for?

    Pay attention to significant changes.

    For example:

    • Is cash increasing or declining?
    • Are customer receivables growing?
    • Are liabilities increasing?
    • Are loans being paid down?
    • Are there unusual or unexplained balances?

    The Balance Sheet can reveal things that aren’t obvious from the P&L alone.

    3. Cash Flow Statement

    What does it tell you?

    Where is the cash coming from, and where is it going?

    This is particularly important because profit and cash are not the same thing.

    You can have a profitable month and still experience cash-flow pressure.

    For example, imagine your HVAC business completes $50,000 of work in June.

    You record the revenue.

    But if several customers don’t pay until July or August, you may not actually have that $50,000 available in June.

    Meanwhile, payroll, materials, fuel, rent, and vendor bills still need to be paid.

    A cash flow report helps you understand how cash is moving through the business.

    What should you look for?

    Ask:

    • Is the business generating enough operating cash?
    • Are large amounts of cash tied up in receivables?
    • Are loan payments affecting cash?
    • Are there significant equipment purchases?
    • Is cash consistently declining?

    Understanding cash flow can help you avoid being caught off guard by a shortage of available cash.

    4. Accounts Receivable Aging Report

    What does it tell you?

    Who owes you money—and how long have they owed it?

    If you invoice customers, this report can be extremely useful.

    An A/R aging report typically organizes outstanding invoices based on how long they’ve been unpaid.

    For example:

    • Current
    • 1–30 days
    • 31–60 days
    • 61–90 days
    • 90+ days

    Imagine you have $80,000 in outstanding customer invoices.

    That number alone doesn’t tell you everything.

    If $70,000 is current and only $10,000 is significantly overdue, the situation is very different from having $50,000 sitting unpaid for more than 90 days.

    What should you look for?

    Pay particular attention to older balances.

    Ask:

    • Which customers are overdue?
    • How long have they been outstanding?
    • Are there customers who consistently pay late?
    • Are there invoices that need follow-up?
    • Are there balances that may need investigation?

    Getting paid for the work you’ve already completed is an important part of managing cash flow.

    5. Accounts Payable Aging Report

    What does it tell you?

    What does your business owe—and when is it due?

    An A/P aging report helps you understand outstanding vendor obligations.

    It can show:

    • Current bills
    • Upcoming payments
    • Past-due bills
    • Vendor balances
    • Aging of outstanding obligations

    For a service business, this might include suppliers for materials, equipment vendors, software providers, and other business expenses.

    What should you look for?

    Ask:

    • What bills are due soon?
    • Are any bills overdue?
    • Are vendor balances unusually high?
    • Are there duplicate or old bills?
    • Do you have enough cash to cover upcoming obligations?

    Knowing what you owe can help you plan rather than react.


    How to Read These Reports Together

    One of the biggest mistakes business owners make is looking at each report in isolation.

    The real value comes from connecting the information.

    Imagine your P&L shows a healthy profit.

    That sounds good.

    But then you look at your Balance Sheet and see that accounts receivable has increased significantly.

    Your A/R aging report shows that several large invoices are more than 60 days old.

    Your cash flow report shows that available cash is tightening.

    Now you have a much clearer picture.

    The business may be profitable—but cash is being tied up in unpaid customer invoices.

    That’s the kind of insight that individual reports may not provide on their own.

    Think of the reports as pieces of the same financial picture:

    P&L → Profitability

    Balance Sheet → Financial position

    Cash Flow → Movement of cash

    A/R Aging → Money customers owe you

    A/P Aging → Money you owe others

    Together, they can give you a much more complete view of your business.


    How Often Should You Review Your Financial Reports?

    For many small businesses, monthly is a practical starting point.

    Monthly reporting gives you enough information to identify trends without overwhelming you with daily fluctuations.

    However, some businesses may benefit from reviewing certain information more frequently.

    For example:

    • Cash position may need weekly monitoring
    • A/R may need frequent follow-up
    • High-volume businesses may review sales more often
    • Large businesses may use daily or weekly dashboards

    The important thing is consistency.

    A report isn’t very useful if you generate it once and never look at it again.


    The Reports You Need Depend on Your Business

    The five reports discussed here provide a strong foundation for many small businesses.

    But your business may need additional information.

    Depending on your operations, you might also benefit from:

    • Sales by customer
    • Sales by service
    • Job profitability
    • Budget vs. actual
    • Expense analysis
    • Inventory reports
    • Technician or department performance
    • Customer concentration reports

    For example, an HVAC business may want to understand whether certain service types or jobs are producing stronger margins.

    The goal isn’t to create dozens of reports.

    The goal is to have the right information for the decisions you need to make.


    What If Your Financial Reports Don’t Look Right?

    Sometimes the problem isn’t the report.

    It’s the bookkeeping behind it.

    If your financial reports contain unusual numbers, unexplained balances, or results that don’t match what you know about the business, don’t simply ignore them.

    Start by asking:

    • Are all transactions recorded?
    • Are bank accounts reconciled?
    • Are credit cards reconciled?
    • Are transactions categorized correctly?
    • Is A/R current?
    • Is A/P current?
    • Are there duplicate transactions?
    • Are there old or unexplained balances?

    Reliable reports depend on reliable underlying records.

    That’s one reason we emphasize the importance of accurate books.


    How Monthly Bookkeeping Makes Reporting Easier

    Financial reports don’t appear out of nowhere.

    They depend on the bookkeeping process behind them.

    A consistent monthly bookkeeping process can include:

    • Recording transactions
    • Categorizing income and expenses
    • Reconciling bank accounts
    • Reconciling credit cards
    • Reviewing accounts receivable
    • Reviewing accounts payable
    • Investigating unusual transactions
    • Reviewing financial reports

    When these tasks are completed consistently, your monthly financial reports become much more useful.

    Instead of spending hours trying to reconstruct what happened, you can focus on understanding the numbers and deciding what to do next.


    Why Financial Reports Matter for HVAC and Service Businesses

    For HVAC and service-based businesses, financial reports can provide insight into areas that directly affect profitability and cash flow.

    Profit & Loss

    Are labor and material costs growing faster than revenue?

    Balance Sheet

    How much cash, equipment, and receivables does the business have?

    Cash Flow

    Can you cover payroll, vendors, vehicle expenses, and other upcoming obligations?

    A/R Aging

    Are customers paying promptly after services are completed?

    A/P Aging

    Are vendor obligations increasing?

    These reports can help answer practical questions such as:

    Can we afford another technician?

    Can we purchase another service vehicle?

    Are our margins improving?

    Do we have enough cash for a slower season?

    Are customers taking too long to pay?

    Those aren’t just accounting questions.

    They’re business decisions.


    How a Bookkeeper Can Help

    You don’t need to become an accountant to understand your business finances.

    A professional bookkeeper can help maintain the records that produce your monthly financial reports and help ensure those reports are based on organized, current information.

    For HVAC and service-based businesses, monthly bookkeeping support may include:

    • Transaction categorization
    • Bank reconciliation
    • Credit card reconciliation
    • Accounts receivable
    • Accounts payable
    • Monthly financial reporting

    The goal isn’t to overwhelm you with accounting terminology.

    It’s to give you clear financial information you can actually use.

    At Prime Ledger Bookkeeping, we help HVAC and service-based businesses maintain organized books and monthly financial reports so owners can spend less time worrying about their numbers and more time running their businesses.


    Key Takeaways

    Monthly financial reports aren’t just for tax preparation. They’re tools for running your business.

    The five reports every owner should understand are:

    Profit & Loss — shows profitability

    Balance Sheet — shows financial position

    Cash Flow Statement — shows how cash moves

    A/R Aging — shows who owes you and how overdue those balances are

    A/P Aging — shows what you owe and what’s coming due

    But don’t stop at simply generating the reports.

    Review them. Compare them. Ask questions. Look for changes.

    The real value comes from using the information to make better decisions.


    Frequently Asked Questions

    What financial reports should a small business review monthly?

    Many small businesses can benefit from reviewing the Profit & Loss, Balance Sheet, Cash Flow Statement, Accounts Receivable Aging, and Accounts Payable Aging reports each month. The exact reports needed depend on the business.

    What is the most important financial report for a small business?

    There isn’t one report that is most important for every business. The Profit & Loss is useful for understanding profitability, while the Balance Sheet, Cash Flow, A/R, and A/P reports provide other important parts of the financial picture.

    How often should a business review financial reports?

    Many small businesses should review their financial reports monthly. Certain information, such as cash and accounts receivable, may need to be monitored more frequently depending on the business.

    Why is a Profit & Loss statement important?

    A Profit & Loss statement shows revenue, expenses, and resulting profit or loss over a specific period. It can help business owners understand whether the business is profitable and identify changes in income and expenses.

    Why is the Balance Sheet important?

    The Balance Sheet provides a snapshot of what a business owns, what it owes, and its equity at a specific point in time. It can reveal financial changes that may not be obvious from the Profit & Loss statement.

    Do small businesses need a Cash Flow Statement?

    Not every small business needs a formal Cash Flow Statement every month, but understanding cash inflows and outflows is important for virtually every business. Cash flow information can help owners anticipate shortages and plan for upcoming obligations.

    What is an A/R aging report?

    An Accounts Receivable Aging report shows outstanding customer invoices and categorizes them based on how long they have been unpaid. It can help business owners identify overdue invoices that may require follow-up.

    What is an A/P aging report?

    An Accounts Payable Aging report shows outstanding vendor bills and organizes them according to how long they have been unpaid. It helps business owners understand upcoming and overdue obligations.

    Can a bookkeeper prepare monthly financial reports?

    Yes. A bookkeeper can maintain the underlying financial records, reconcile accounts, review A/R and A/P, and prepare or provide monthly financial reports based on the bookkeeping system.


    Conclusion

    You don’t need to be an accountant to understand your business finances.

    But you do need reliable information.

    Monthly financial reports can help you move beyond simply looking at your bank balance or total sales and start understanding what’s actually happening inside your business.

    Your Profit & Loss can show whether you’re profitable.

    Your Balance Sheet can show what you own and owe.

    Your cash flow information can show how money is moving.

    Your A/R report can show who still owes you.

    And your A/P report can show what you need to pay.

    Together, these reports give you a clearer financial picture—and that picture can help you make better decisions.

    If you’re not currently receiving and reviewing these reports each month, it may be time to establish a more consistent bookkeeping process.

    At Prime Ledger Bookkeeping, we help HVAC and service-based businesses maintain accurate books and receive useful monthly financial reports without having to manage the bookkeeping themselves.

    Your numbers should do more than record what happened. They should help you decide what to do next.

    Accurate Books. Clear Decisions. Peace of Mind.


    Related Articles

    Why Accurate Books Matter

    Learn why reliable and current financial records are essential for making better business decisions.

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    Understand what a bookkeeper does and how ongoing bookkeeping supports your business.

    Still Using Spreadsheets? Here’s the Risk.

    Learn the warning signs that your spreadsheet-based bookkeeping system may no longer be keeping up with your business.

    Let’s Get Your Books Back on Track

    If your financial records aren’t accurate or current, learn how bookkeeping cleanup can help.

    5 Signs It’s Time to Hire a Bookkeeper

    Not sure whether professional bookkeeping support makes sense for your business? Start here.


  • Why Accurate Books Matter

    Why Accurate Books Matter

    Your Books Are More Than a Record of What Happened

    Imagine you’re considering hiring another technician.

    You think the business can afford it.

    Revenue has been strong. Customers are coming in. Your bank account looks healthy.

    But then you look at your financial reports—and you’re not completely sure the numbers are right.

    Are your expenses fully recorded?

    Have all your customer payments been entered?

    Are your bank accounts reconciled?

    Are there old transactions sitting in the wrong accounts?

    If you’re not confident in your numbers, making an important business decision becomes a guessing game.

    That’s why accurate books matter.

    Your books aren’t simply a record of what happened in the past. They provide the financial information you use to understand your business today and make decisions about tomorrow.

    For small-business owners, especially those running HVAC and other service-based businesses, reliable financial records can help answer some important questions:

    Are we actually profitable?

    Where is our money going?

    Can we afford to hire?

    Which parts of the business are performing well?

    Do we have enough cash for our upcoming obligations?

    Let’s look at seven practical reasons accurate financial records can make such a difference.


    Table of Contents

    1. What Does It Mean to Have Accurate Books?
    2. 7 Reasons Accurate Books Matter
    3. What Happens When Your Books Aren’t Accurate?
    4. Accurate Books vs. Current Books
    5. How Do You Know If Your Books Are Accurate?
    6. How Regular Bookkeeping Helps
    7. Why Accurate Books Matter for HVAC and Service Businesses
    8. What Can You Do If Your Books Aren’t Accurate?
    9. Why Professional Bookkeeping Can Help
    10. A Simple Monthly Bookkeeping Checklist
    11. Key Takeaways
    12. Frequently Asked Questions
    13. Conclusion

    What Does It Mean to Have Accurate Books?

    Before discussing why accuracy matters, let’s clarify what we mean by accurate books.

    Accurate bookkeeping doesn’t mean your financial records will never need an adjustment.

    The IRS also emphasizes that businesses should maintain records that clearly show their income and expenses and support the transactions recorded in their books. IRS: What Kind of Records Should I Keep?

    It means your records reasonably reflect the financial activity of your business and are supported by the underlying transactions and documentation.

    Generally, this means:

    • Transactions are recorded completely
    • Transactions are categorized appropriately
    • Bank and credit card accounts are reconciled
    • Customer payments are properly recorded
    • Vendor bills and payments are properly recorded
    • Duplicate transactions are identified
    • Unusual balances are investigated
    • Financial reports reflect the underlying records
    • Books are updated consistently

    There’s another important distinction:

    Accurate Doesn’t Necessarily Mean Current

    Your books could be accurate through March—but if it’s August and nothing has been recorded since March, those books aren’t very useful for understanding what’s happening today.

    For business decision-making, you want both:

    Accurate + Current


    7 Reasons Accurate Books Matter

    1. Accurate Books Help You Understand Your True Profitability

    Revenue is only part of the story.

    A business might generate $100,000 in sales and still struggle financially because of labor, materials, vehicle expenses, insurance, rent, software, and other operating costs.

    Your Profit & Loss statement helps you see the relationship between your revenue and expenses.

    But that only works when the underlying records are reliable.

    If expenses are missing or transactions are categorized incorrectly, your reported profit may not reflect your actual results.

    For an HVAC business, this could make it harder to determine whether the business is truly profitable after considering labor, materials, fuel, equipment, and other operating costs.

    Accurate books help you see the difference between making sales and actually making money.

    2. They Help You Understand Where Your Money Is Going

    Have you ever looked at your bank account and wondered:

    “Where did all the money go?”

    Your bank statement can show you that money left the account.

    But your bookkeeping should help explain why.

    Was it:

    • Payroll?
    • Materials?
    • Fuel?
    • Equipment?
    • Advertising?
    • Insurance?
    • Vendor payments?
    • Owner draws?
    • Loan payments?

    When transactions are properly categorized, your financial reports can reveal spending patterns that aren’t obvious from a bank statement alone.

    That information can help you identify expenses that are increasing, areas where you may be overspending, and opportunities to improve profitability.

    3. Accurate Books Help You Make Better Business Decisions

    Small-business owners make decisions every day.

    Should you hire another employee?

    Should you purchase another service vehicle?

    Can you afford new equipment?

    Should you expand into another service area?

    Should you increase your marketing budget?

    These decisions have financial consequences.

    You don’t need perfect financial information to make every decision—but you need information you can reasonably trust.

    When your books are accurate and current, you have a much stronger foundation for evaluating your options.

    Instead of asking:

    “I think we can afford this.”

    You can ask:

    “Based on our current revenue, expenses, cash flow, and upcoming obligations, can we reasonably afford this?”

    That’s a much better business conversation.

    4. They Help You Manage Cash Flow

    Profit and cash are not the same thing.

    A business can show a profit and still experience cash-flow pressure.

    For example, an HVAC company may complete several large jobs and record the revenue, but if customers haven’t paid yet, that money isn’t necessarily available in the bank.

    At the same time, payroll, vendor bills, loan payments, and other obligations may still be due.

    Accurate bookkeeping helps you understand both sides:

    What’s coming in?

    What’s going out?

    What’s still owed to you?

    What do you need to pay?

    This gives you a clearer picture of your cash position and upcoming obligations.

    5. They Help You Stay on Top of Customer Payments

    For many service businesses, getting paid doesn’t always happen at the same time the work is completed.

    You may invoice a customer today and receive payment weeks later.

    That’s why accounts receivable matters.

    Accurate records can help you see:

    • Which invoices are outstanding
    • How much customers owe
    • How long invoices have been outstanding
    • Whether payments were properly applied
    • Which customers may need follow-up

    Without reliable A/R records, it’s easier for outstanding invoices to get overlooked.

    And overlooked invoices can eventually become a cash-flow problem.

    6. They Help You Know What You Owe

    The same principle applies to your vendors.

    Your accounts payable records should help you understand your outstanding obligations.

    For example:

    • Which vendor bills are unpaid?
    • When are payments due?
    • Have payments been recorded correctly?
    • Are there duplicate bills?
    • Are vendor credits properly applied?

    Reliable A/P information can help you plan upcoming payments and avoid unpleasant surprises.

    It also gives you a clearer picture of your actual business obligations.

    7. They Help You Spot Problems Earlier

    Perhaps one of the biggest benefits of accurate books is that they can help you identify problems before they become bigger problems.

    Imagine your financial reports show that:

    • Labor costs are increasing
    • Material costs are eating into margins
    • Customer payments are slowing down
    • A particular expense category has suddenly increased
    • Cash reserves are declining
    • A Balance Sheet account has an unusual balance

    If your books are current and reliable, you have a chance to investigate.

    If your books are six months behind, you may not discover the problem until much later.

    Good bookkeeping doesn’t just tell you what happened. It helps you notice what needs your attention.


    What Happens When Your Books Aren’t Accurate?

    The opposite of accurate bookkeeping can create more than an accounting headache.

    It can affect the way you run your business.

    You May Overestimate Profitability

    If expenses are missing, your reported profit could look better than reality.

    You May Underestimate Expenses

    Poor categorization can make it difficult to see where money is actually being spent.

    You May Make Decisions Using Outdated Information

    If your books aren’t current, your financial reports may not reflect the business you’re running today.

    You May Miss Outstanding Customer Payments

    If A/R isn’t maintained properly, invoices can slip through the cracks.

    You May Be Surprised by Upcoming Obligations

    If A/P isn’t accurate, you may not have a clear picture of what you owe.

    You May Spend More Time Fixing Problems Later

    Small bookkeeping issues can become harder to resolve when they’re allowed to accumulate.


    Accurate Books vs. Current Books

    This distinction deserves special attention.

    You can have accurate but outdated books.

    For example:

    Your bookkeeping is complete and accurate through March.

    Today is August.

    Nothing has been recorded since March.

    The March numbers may be accurate—but they don’t tell you what’s happening in August.

    You can also have current but inaccurate books.

    Maybe transactions are being entered every week, but they’re being categorized incorrectly or the bank accounts aren’t being reconciled.

    In that case, your books are current but still unreliable.

    The goal is both.

    Accurate books + Current books = Useful financial information

    That’s why consistent bookkeeping matters.


    How Do You Know If Your Books Are Accurate?

    You don’t have to be an accountant to perform a basic health check of your books.

    Ask yourself:

    Are your bank accounts reconciled?

    Your book balance should be compared against your bank statements regularly.

    Are your credit cards reconciled?

    Credit card activity should also be reviewed and reconciled.

    Are transactions categorized appropriately?

    Expenses should be recorded in accounts that accurately represent the nature of the spending.

    Are there unexplained balances?

    Unusual or old balances should be investigated rather than ignored.

    Is your accounts receivable current?

    You should have a reasonable understanding of what customers owe you.

    Is your accounts payable current?

    You should know what you owe vendors and when payments are due.

    Do your financial reports make sense?

    Look at your Profit & Loss and Balance Sheet.

    If something looks unusual, investigate it.

    Are your books updated consistently?

    Financial information is much more useful when it reflects recent business activity.

    If several of these questions make you uncomfortable, it may be time to take a closer look at your bookkeeping.


    How Regular Bookkeeping Helps

    Accurate books aren’t created once a year.

    They’re maintained through a consistent process.

    For many small businesses, monthly bookkeeping can include:

    • Recording and categorizing transactions
    • Reconciling bank accounts
    • Reconciling credit cards
    • Reviewing accounts receivable
    • Reviewing accounts payable
    • Updating financial reports
    • Investigating unusual transactions
    • Reviewing financial trends

    The benefit isn’t simply having someone enter transactions.

    It’s having a repeatable process that keeps your financial information reliable.

    That means fewer surprises and less time trying to reconstruct what happened months ago.


    Why Accurate Books Matter for HVAC and Service Businesses

    Every business is different, but HVAC and other service-based businesses often deal with financial activity that makes good bookkeeping particularly useful.

    For example:

    Labor

    Are labor costs increasing faster than revenue?

    Materials

    Are material costs affecting your margins?

    Service Vehicles

    Can you afford another vehicle or the replacement of an existing one?

    Customer Payments

    Are customers paying within the expected timeframe?

    Seasonal Cash Flow

    Do you have enough cash available during slower periods?

    Job Profitability

    Are certain types of jobs or services producing stronger margins?

    Growth

    Can the business realistically support another technician or additional equipment?

    You don’t want to answer these questions based on assumptions.

    You want your financial records to give you useful information.


    What Can You Do If Your Books Aren’t Accurate?

    If you discover that your books aren’t where they should be, don’t panic.

    Start by determining the scope of the problem.

    Ask:

    1. When were the books last reconciled?
    2. Which accounts need attention?
    3. Are transactions missing or duplicated?
    4. Are there unusual or unexplained balances?
    5. Is accounts receivable accurate?
    6. Is accounts payable accurate?
    7. Do the financial reports reflect what you know about the business?

    If the problems are minor, you may be able to address them as part of your regular bookkeeping.

    If the books are significantly behind or contain multiple issues, a bookkeeping cleanup may be a better starting point.

    For more on that process, see:

    Let’s Get Your Books Back on Track


    Why Professional Bookkeeping Can Help

    You don’t necessarily need to become an accounting expert to understand your business finances.

    A professional bookkeeper can help maintain the records behind your financial reports so you can spend more time using the information rather than trying to create it.

    For HVAC and service-based businesses, that can mean having someone regularly handle:

    • Transaction categorization
    • Bank reconciliations
    • Credit card reconciliations
    • Accounts receivable
    • Accounts payable
    • Monthly financial reports
    • Bookkeeping cleanup when needed

    The goal isn’t simply to keep your books busy.

    It’s to keep them useful.


    A Simple Monthly Bookkeeping Checklist

    If you manage your own bookkeeping, here’s a simple checklist to help keep your records reliable.

    Every month:

    ☐ Record all business transactions

    ☐ Review and categorize transactions

    ☐ Reconcile bank accounts

    ☐ Reconcile credit cards

    ☐ Review accounts receivable

    ☐ Review accounts payable

    ☐ Investigate unusual balances

    ☐ Review your Profit & Loss

    ☐ Review your Balance Sheet

    ☐ Compare results with previous months

    ☐ Address problems before moving into the next month

    You don’t need a complicated system.

    You need a consistent one.


    Key Takeaways

    Accurate bookkeeping isn’t just about keeping financial records organized.

    It’s about having information you can use.

    Accurate books can help you:

    ✅ Understand your true profitability

    ✅ See where your money is going

    ✅ Make better business decisions

    ✅ Manage cash flow

    ✅ Stay on top of customer payments

    ✅ Understand vendor obligations

    ✅ Spot potential problems earlier

    And remember:

    Accurate books that are six months behind still aren’t giving you the information you need today.

    The goal is to maintain financial records that are both accurate and current.


    Frequently Asked Questions

    Why are accurate books important for a small business?

    Accurate books give business owners reliable financial information about revenue, expenses, profitability, cash flow, customer balances, and vendor obligations. This information can support better business decisions.

    What happens if my books aren’t accurate?

    Inaccurate books can lead to misleading financial reports and make it harder to understand profitability, cash flow, expenses, receivables, and obligations. They can also make it more difficult to identify problems early.

    How often should bookkeeping be updated?

    The appropriate frequency depends on the business, but many small businesses benefit from maintaining their books monthly or more frequently when transaction volume requires it. The important thing is that the records remain both accurate and current.

    Can my books be accurate but outdated?

    Yes. Your books can be accurate through a particular date but still be outdated if more recent transactions haven’t been recorded. Accurate and current records are both important for useful financial reporting.

    How can I tell if my books are accurate?

    Start by checking whether your bank and credit card accounts are reconciled, transactions are properly categorized, A/R and A/P are current, unusual balances have been investigated, and your financial reports make sense based on what you know about the business.

    Can a bookkeeper help keep my books accurate?

    Yes. A bookkeeper can maintain transactions, reconcile accounts, review A/R and A/P, and prepare regular financial reports. A consistent bookkeeping process can help keep your records accurate and current.

    What if my books are already inaccurate?

    Start by identifying the scope of the problem. If there are significant errors, unreconciled accounts, missing transactions, or old balances, a bookkeeping cleanup may be appropriate before establishing a regular monthly bookkeeping process.


    Conclusion

    Accurate books give you more than organized financial records—they give you a clearer view of your business.

    When your books are accurate and current, you can better understand your profitability, manage cash flow, stay on top of customer and vendor balances, and make decisions based on reliable information rather than guesswork.

    For HVAC and service-based business owners, that clarity can make a real difference.

    Whether you’re deciding whether to hire another technician, purchase equipment, take on a new project, or simply understand where your money is going, your financial records should give you confidence in the numbers you’re using.

    And if your books aren’t where they should be, you don’t have to figure everything out at once.

    Start by identifying what’s inaccurate, what’s outdated, and what needs attention. From there, you can work toward getting your books clean, current, and reliable.

    If maintaining accurate books has become difficult to manage on your own, professional monthly bookkeeping can help you stay organized and keep your financial information current.

    Prime Ledger Bookkeeping helps HVAC and service-based businesses maintain organized, reliable financial records so they can spend less time worrying about their books and more time running their business.

    Accurate Books. Clear Decisions. Peace of Mind.


    Related Articles

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    Learn what a bookkeeper actually does and how consistent bookkeeping can support your business.

    Bookkeeping vs. Accounting Explained

    Understand the difference between bookkeeping and accounting and how the two functions work together.

    Why Your Bank Balance Doesn’t Match Your Books

    Learn why your bank balance and books may show different numbers and how to investigate the difference.

    Let’s Get Your Books Back on Track

    Learn how bookkeeping cleanup can help identify problems, organize your records, and get your books back on track.

    5 Signs It’s Time to Hire a Bookkeeper

    Not sure whether it’s time to get professional bookkeeping help? These five signs can help you decide.

  • Why Your Bank Balance Doesn’t Match Your Books

    Why Your Bank Balance Doesn’t Match Your Books

    Your Bank Says One Number. Your Books Say Another.

    You check your business bank account.

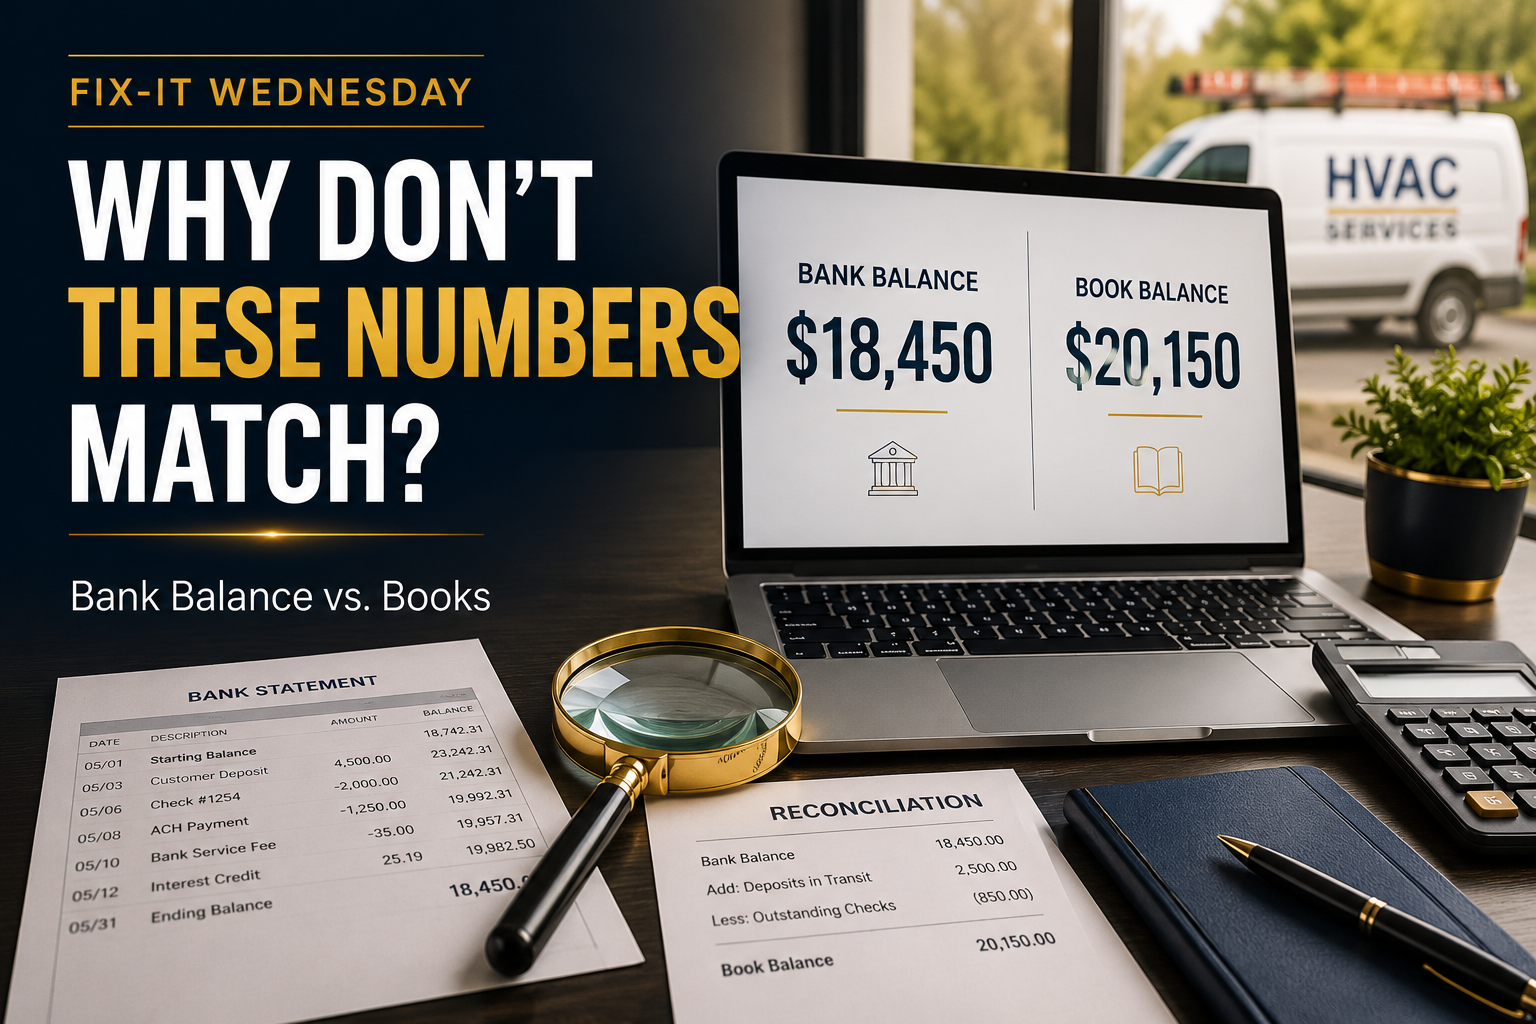
    The balance says $18,450.

    Then you open your accounting software.

    The balance says $20,150.

    And you immediately wonder:

    “Which number is wrong?”

    When your bank balance doesn’t match books, it’s easy to wonder which number is wrong.

    For many small-business owners, seeing two different numbers can be alarming.

    But here’s the good news:

    A difference doesn’t automatically mean your bookkeeping is wrong.

    Sometimes the difference is simply caused by timing.

    A check may have been recorded in your books but hasn’t cleared the bank yet.

    A deposit may have been recorded but hasn’t reached the bank account.

    A bank fee may have appeared on your statement before it was entered into your accounting system.

    Other times, however, the difference really does indicate a bookkeeping problem.

    The key is knowing why the numbers don’t match.

    In this guide, we’ll walk through seven common reasons your bank balance and books may be different, how to investigate the difference, and what you should avoid doing when trying to reconcile your accounts.

    Table of Contents

    1. Should Your Bank Balance and Books Match?
    2. The 7 Common Reasons Your Balances Don’t Match
    3. How to Find the Difference
    4. Don’t Just Force the Reconciliation
    5. An HVAC Business Example
    6. When a Difference Is a Red Flag
    7. How to Prevent Reconciliation Problems
    8. When to Get Professional Bookkeeping Help
    9. How Prime Ledger Can Help
    10. Key Takeaways
    11. Frequently Asked Questions
    12. Conclusion

    Should Your Bank Balance and Books Match?

    This is the first thing to understand.

    Your bank balance and your book balance don’t necessarily have to be identical at every moment.

    There can be legitimate differences between the two.

    For example, you may write a check today and record it in your accounting system.

    Your books immediately reflect the payment.

    But the recipient may not deposit the check for several days.

    Until the bank processes it, your bank balance won’t reflect the withdrawal.

    That’s a timing difference.

    The same thing can happen with deposits.

    You might record a customer payment in your books on Friday, but the bank may not credit the account until Monday.

    So when your bank balance doesn’t match your books, the first question isn’t:

    “Which number is wrong?”

    It’s:

    “Can I explain the difference?”

    If you can explain it through legitimate timing differences or known transactions that haven’t yet been recorded, that’s very different from an unexplained discrepancy.


    The 7 Common Reasons Your Balances Don’t Match

    1. Outstanding Checks

    An outstanding check is a payment that has been recorded in your books but hasn’t cleared the bank yet.

    For example:

    You issue a $2,000 check to a vendor on August 10.

    You record the payment in your books that day.

    Your book balance decreases by $2,000.

    But the vendor doesn’t deposit the check until August 15.

    Until the check clears, your bank statement won’t reflect that $2,000 withdrawal.

    What happens?

    Books: Payment recorded

    Bank: Payment not yet cleared

    That’s a normal timing difference.

    It doesn’t necessarily mean anything is wrong.

    2. Deposits in Transit

    Deposits in transit are essentially the opposite situation.

    You may have recorded a deposit in your books, but the bank hasn’t processed it yet.

    Imagine an HVAC customer pays a $4,500 invoice on Friday.

    You record the payment and deposit in your accounting system.

    But the funds don’t appear in the bank until Monday.

    Your books show the additional $4,500.

    Your bank doesn’t yet.

    Again, this can be a normal timing difference.

    3. Bank Fees Were Not Recorded

    Sometimes the bank balance is lower than the balance in your books because the bank has charged a fee that hasn’t been recorded in your accounting system.

    Examples could include:

    • Monthly service fees
    • Wire fees
    • Transaction fees
    • Stop-payment fees
    • Other bank charges

    Suppose your bank deducts a $35 service fee.

    Your bank balance decreases immediately.

    But if you haven’t entered the $35 expense into your books, your accounting balance won’t reflect it.

    Now you have a difference that needs to be recorded and reconciled.

    4. Interest or Other Bank Credits Were Missed

    The difference can also work in the opposite direction.

    Your bank may add:

    • Interest income
    • Refunds
    • Credits
    • Other adjustments

    If those amounts haven’t been recorded in your accounting system, your bank balance may be higher than your book balance.

    For example, if your bank adds $25 of interest but your books don’t include it, you’ll have a $25 difference to investigate.

    The solution isn’t complicated in principle:

    Identify the transaction, record it appropriately, and reconcile the account.

    5. Duplicate or Missing Transactions

    Now we’re getting into actual bookkeeping errors.

    A transaction may have been:

    • Entered twice
    • Never entered
    • Recorded for the wrong amount
    • Recorded on the wrong date

    Imagine your business purchased $600 of equipment.

    The transaction accidentally gets entered twice.

    Your books now show a $1,200 expense.

    The bank only shows the actual $600 payment.

    Your balances won’t reconcile because the books contain an extra transaction.

    The same problem can happen when a transaction is missing completely.

    6. A Transaction Was Recorded in the Wrong Account

    This can become particularly confusing when a business has multiple bank accounts.

    Suppose your company has:

    • Operating checking
    • Payroll checking
    • Savings
    • Business credit card

    A $1,000 payment actually came out of your operating account.

    But it was mistakenly recorded against the payroll account.

    The transaction exists in your books.

    The amount may even be correct.

    But it’s associated with the wrong account.

    As a result, one account may appear too high while another appears too low.

    This is one reason it’s important to review which account a transaction was posted to, not just whether the transaction exists.

    7. A Previous Reconciliation Was Incorrect

    Sometimes today’s problem started months ago.

    A previous reconciliation may have been completed incorrectly.

    Perhaps:

    • A transaction was accidentally deleted.
    • A reconciled transaction was changed.
    • A duplicate transaction was created.
    • An opening balance was altered.
    • An adjustment was entered incorrectly.

    If the prior reconciliation was wrong, the current reconciliation may continue to show a difference.

    This is why unexplained reconciliation discrepancies can sometimes require looking backward rather than only reviewing the current month.


    How to Find the Difference

    So what should you actually do when your bank balance doesn’t match books?

    Don’t start by changing random transactions.

    Instead, work through the problem systematically.

    Step 1: Confirm the Correct Bank Statement

    Make sure you’re comparing the correct:

    • Bank account
    • Statement period
    • Statement ending date
    • Statement ending balance

    It sounds obvious, but using the wrong statement period can make a reconciliation impossible.

    Step 2: Compare the Ending Balance

    Look at the ending balance shown on your bank statement.

    Then compare it with the corresponding balance in your accounting system.

    Determine exactly how much the difference is.

    For example:

    Bank: $18,450

    Books: $20,150

    Difference: $1,700

    Now you have a specific number to investigate.

    Step 3: Look for Outstanding Transactions

    Review transactions that have been recorded in your books but haven’t cleared the bank.

    These may include:

    • Outstanding checks
    • Recent electronic payments
    • Deposits in transit

    Timing differences may explain part or all of the discrepancy.

    Step 4: Review Bank Charges and Credits

    Look carefully at your bank statement.

    Check for transactions that aren’t currently recorded in your books.

    Look for:

    • Service fees
    • Interest
    • Bank charges
    • Refunds
    • Other credits or adjustments

    These are often easy to overlook.

    Step 5: Look for Duplicates

    Review your accounting records for duplicate entries.

    Pay particular attention to:

    • Large transactions
    • Recently imported transactions
    • Manually entered transactions
    • Transactions entered both manually and through a bank feed

    A duplicate transaction can create a difference even though the original transaction is correct.

    Step 6: Look for Missing Transactions

    Now work in the opposite direction.

    Is there something on the bank statement that isn’t in your books?

    Go through the statement and compare it with the accounting records.

    Pay attention to:

    • Checks
    • Deposits
    • Electronic payments
    • Bank fees
    • Transfers
    • Interest

    Step 7: Check the Account

    If the transaction exists but the balance still doesn’t make sense, verify that it was recorded in the correct bank account.

    This becomes especially important when the business has multiple accounts.

    Step 8: Review Previous Reconciliations

    If you still can’t explain the difference, don’t assume the current month is the problem.

    Review earlier reconciliations.

    A previous error can carry forward into subsequent periods.


    Don’t Just Force the Reconciliation

    This deserves its own section because it’s one of the most important lessons in this article.

    When your accounting software shows a reconciliation difference, it can be tempting to make an adjustment just to get the numbers to zero.

    But zero isn’t the goal.

    Accuracy is the goal.

    If you enter a random adjustment simply to make the reconciliation balance, you may hide the real problem.

    The books might appear reconciled, but the underlying financial information could still be incorrect.

    That can create additional problems later when you’re reviewing:

    • Profitability
    • Cash flow
    • Financial statements
    • Tax information
    • Accounts receivable
    • Accounts payable

    If you don’t understand why the difference exists, investigate it before making an adjustment.


    An HVAC Business Example

    Let’s look at a realistic example.

    Imagine an HVAC company has a bank balance of $25,000.

    Its accounting system shows $27,500.

    At first, the owner is concerned.

    But the bookkeeper reviews the transactions and finds:

    $2,000 outstanding vendor check

    The check was recorded in the books but hasn’t cleared the bank.

    And:

    $500 deposit in transit

    A customer payment was recorded but hasn’t reached the bank yet.

    Now the difference is understandable.

    The two balances aren’t identical because of timing.

    That is very different from discovering that:

    • A $500 payment was recorded twice
    • A $1,000 bank fee was never recorded
    • A $750 transaction was posted to the wrong bank account

    Those are bookkeeping issues that need to be corrected.

    The important point is:

    Don’t assume every difference is an error—but don’t ignore unexplained differences either.


    When a Difference Is a Red Flag

    A difference deserves closer attention when:

    The amount is significant.

    A small timing difference may be normal.

    A large unexplained difference deserves investigation.

    The difference has no clear explanation.

    If you can’t identify why the balances differ, don’t simply move on.

    The discrepancy keeps appearing.

    If you’re constantly carrying unexplained differences from month to month, your reconciliation process may need attention.

    Previous reconciliations were changed.

    Changes to previously reconciled transactions can create problems that aren’t immediately obvious.

    Your books haven’t been reconciled regularly.

    The longer you go without reconciliation, the harder it can become to identify when the problem started.

    Multiple accounts are affected.

    If money is moving between several bank accounts and the balances don’t make sense, the issue may be more complicated than a simple timing difference.


    How to Prevent Reconciliation Problems

    The best reconciliation problem is the one you don’t have to fix later.

    A consistent monthly bookkeeping process can help.

    Reconcile Your Accounts Regularly

    Don’t wait several months before comparing your books with your bank statements.

    Regular reconciliation makes discrepancies easier to identify while the transactions are still fresh.

    Keep Business and Personal Transactions Separate

    Mixing personal and business activity can make your financial records much more difficult to maintain and reconcile.

    Keeping business activity in dedicated business accounts can simplify the bookkeeping process.

    Review Your Books Before Closing the Month

    Look for unusual transactions, duplicate entries, missing transactions, and unexplained balances before considering the month complete.

    Don’t Ignore Small Differences

    A $10 difference may not seem important.

    But if you repeatedly ignore small discrepancies, they can become much harder to trace later.

    The goal isn’t to obsess over every cent.

    It’s to establish a process that makes unexplained differences visible and manageable.


    When to Get Professional Bookkeeping Help

    If you’re comfortable working through simple reconciliation differences, you may be able to resolve many issues yourself.

    But professional help may make sense when:

    • You have several months of unreconciled accounts.
    • Your books don’t balance consistently.
    • You have multiple bank and credit card accounts.
    • Previous reconciliations contain errors.
    • Transactions have been deleted or changed after reconciliation.
    • You have a large number of unexplained transactions.
    • You aren’t confident in the accuracy of your financial reports.

    The longer a bookkeeping problem remains unresolved, the more difficult it can become to determine where it started.

    Getting help early can sometimes save considerable time and cleanup work later.


    How Prime Ledger Can Help

    At Prime Ledger Bookkeeping, we help HVAC and service-based businesses keep their financial records organized, reconciled, and current.

    Our services include:

    • Monthly bookkeeping
    • Bank and credit card reconciliations
    • Accounts receivable
    • Accounts payable
    • Bookkeeping cleanup and catch-up
    • Financial reporting
    • QuickBooks Online support

    We don’t believe reconciliation is simply about making two numbers match.

    It’s about making sure the financial records behind those numbers are accurate.

    Because when you can trust your books, you can make better decisions about your business.

    Accurate Books. Clear Decisions. Peace of Mind.


    🔧 Key Takeaways

    If your bank balance doesn’t match your books, don’t panic—and don’t immediately force the reconciliation.

    Remember:

    Not every difference is an error. Timing differences can occur because of outstanding checks and deposits in transit.

    Some differences require correction. Missing transactions, duplicate entries, bank fees, and incorrectly posted transactions can create real discrepancies.

    Find the reason before making an adjustment. Making a random adjustment just to reach zero can hide an underlying problem.

    Review previous reconciliations if the current difference can’t be explained.

    Reconcile regularly to catch problems while they’re still easy to investigate.

    Most importantly:

    A reconciled account should be accurate—not simply made to balance.


    Frequently Asked Questions

    Why doesn’t my bank balance match my books?

    Your bank balance may differ from your book balance because of timing differences, such as outstanding checks or deposits in transit, or because of bookkeeping issues such as missing, duplicate, or incorrectly recorded transactions.

    Should my bank balance and book balance always match?

    Not necessarily. Legitimate timing differences can cause the balances to differ temporarily. The important thing is that the difference can be explained and properly accounted for during reconciliation.

    Why doesn’t my bank balance match QuickBooks?

    Common reasons include outstanding transactions, deposits that haven’t cleared, bank fees that haven’t been recorded, duplicate or missing transactions, transactions posted to the wrong account, or errors from previous reconciliations.

    What is a bank reconciliation?

    A bank reconciliation is the process of comparing the transactions and balance in your accounting records with the information on your bank statement and identifying differences that need to be explained or corrected.

    What are outstanding checks?

    Outstanding checks are checks that have been recorded in your books but have not yet cleared your bank account. They can create a temporary difference between the bank balance and book balance.

    What are deposits in transit?

    Deposits in transit are deposits recorded in your books that have not yet been processed or credited by the bank. They can create a temporary difference during reconciliation.

    How do I fix a bank reconciliation discrepancy?

    Start by confirming the correct account and statement period, then compare the ending balances and review outstanding transactions, deposits, bank fees, missing or duplicate transactions, and account assignments. If the difference remains unexplained, review previous reconciliations or seek professional bookkeeping assistance.

    Should I force QuickBooks to reconcile?

    No. You should generally identify and understand the reason for a reconciliation difference rather than making an arbitrary adjustment simply to force the account to balance. An unexplained adjustment can hide an underlying bookkeeping error.


    Conclusion

    Seeing your bank balance and books show different numbers can be unsettling.

    But a difference doesn’t automatically mean something is wrong.

    Sometimes the explanation is simple:

    A check hasn’t cleared.

    A deposit is still in transit.

    A bank fee hasn’t been recorded yet.

    Other times, the difference points to a genuine bookkeeping problem.

    The important thing is to understand the difference instead of simply making it disappear.

    When your bank balance doesn’t match your books, work through the reconciliation systematically. Check for timing differences, missing transactions, duplicates, bank charges, incorrect account assignments, and previous reconciliation issues.

    And if you can’t determine why the numbers don’t match, don’t be afraid to get professional help.

    Because the goal of bookkeeping isn’t simply to make the numbers balance.

    The goal is to make sure the numbers are accurate enough to trust.

    And when you can trust your books, you can make business decisions with greater confidence.


    🔧 Can’t Figure Out Why Your Numbers Don’t Match?

    If your bank balance and books don’t match—and you can’t determine why—Prime Ledger Bookkeeping can help.

    We help HVAC and service-based businesses with bank reconciliations, bookkeeping cleanup, monthly bookkeeping, accounts receivable, accounts payable, and financial reporting.

    Schedule a free bookkeeping consultation.

    Let’s identify what’s happening with your books and help you get your financial records back on track.

    Accurate Books. Clear Decisions. Peace of Mind.


    Related Articles

    📚 Bookkeeping Basics Monday

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    Learn what a professional bookkeeper does, including how regular reconciliations help keep financial records accurate.

    Bookkeeping vs. Accounting Explained

    Understand where bookkeeping fits within your broader financial system and how it works alongside accounting.

    🔧 Fix-It Wednesday

    Your Books Are Months Behind—Now What?

    If your reconciliations haven’t been done in months, start here with our practical catch-up bookkeeping guide.

    📈 Finance Friday

    5 Signs It’s Time to Hire a Bookkeeper

    Recurring reconciliation problems may be one sign that your business has outgrown DIY bookkeeping.

  • Bookkeeping vs. Accounting Explained

    Bookkeeping vs. Accounting Explained

    Bookkeeping and Accounting Are Not the Same Thing

    If you’ve ever wondered about bookkeeping vs. accounting, you’re not alone.

    Small-business owners often hear the two terms used interchangeably.

    You might even have an accountant who handles your taxes while someone else handles your QuickBooks—and wonder:

    “So what’s the difference?”

    The simplest explanation is this:

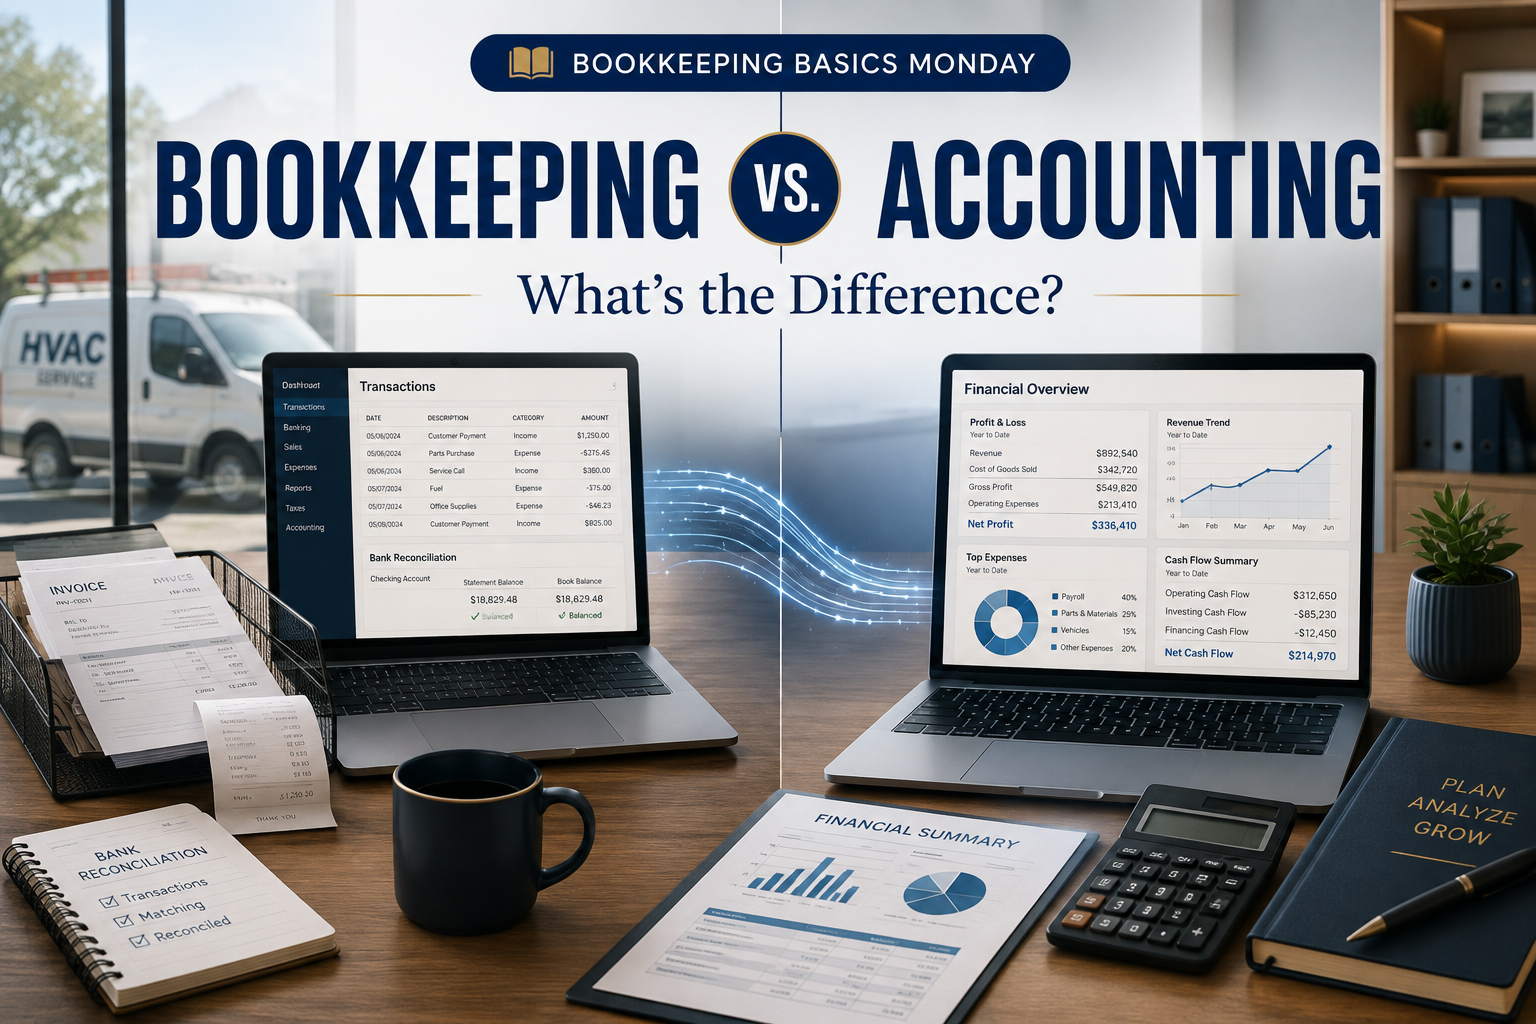
    Bookkeeping focuses on recording and organizing your business’s financial transactions. Accounting takes that financial information and uses it for analysis, reporting, tax work, planning, and decision-making.

    Think of it this way:

    Bookkeeping records the financial story.

    Accounting helps you understand what the story means.

    The two functions are different, but they work closely together.

    And understanding the difference can help you determine what kind of financial support your business actually needs.

    In this guide, we’ll explain bookkeeping vs. accounting in plain English, look at what bookkeepers and accountants typically do, and explain when your small business may need one—or both.


    Table of Contents

    1. The Simple Difference Between Bookkeeping and Accounting
    2. What Does a Bookkeeper Do?
    3. What Does an Accountant Do?
    4. Bookkeeper vs. Accountant: Side-by-Side
    5. How Bookkeeping and Accounting Work Together
    6. What Does This Look Like for an HVAC Business?
    7. Do I Need a Bookkeeper, an Accountant, or Both?
    8. Can One Person Do Both?
    9. When Should You Hire a Bookkeeper?
    10. Key Takeaways
    11. Frequently Asked Questions
    12. Conclusion

    The Simple Difference Between Bookkeeping and Accounting

    Let’s start with the simplest possible explanation.

    Bookkeeping is primarily about recording and organizing financial information.

    A bookkeeper helps maintain the day-to-day financial records of a business.

    That can include:

    • Recording income and expenses
    • Categorizing transactions
    • Reconciling bank accounts
    • Reconciling credit cards
    • Tracking customer invoices
    • Tracking vendor bills
    • Maintaining financial records
    • Preparing routine financial reports

    Accounting goes a step further.

    An accountant may take those organized records and use them for:

    • Financial analysis
    • Tax preparation
    • Tax planning
    • Financial statement analysis
    • Budgeting
    • Forecasting
    • Business planning
    • Advisory services

    This is the basic distinction behind bookkeeping vs. accounting.

    But there’s more overlap between the two than this simple definition might suggest.


    What Does a Bookkeeper Do?

    A bookkeeper’s primary responsibility is maintaining accurate and organized financial records.

    Think about everything that happens financially in a business every day.

    A customer pays an invoice.

    A vendor sends a bill.

    The business purchases supplies.

    An employee-related transaction occurs.

    A credit card is charged.

    Money moves between accounts.

    All of these activities need to be recorded correctly.

    That’s where bookkeeping comes in.


    Recording and Categorizing Transactions

    A bookkeeper records financial transactions and assigns them to the appropriate accounts.

    For example, an HVAC business might purchase:

    • Refrigerant
    • Replacement parts
    • Tools
    • Fuel
    • Office supplies
    • Equipment

    Those transactions need to be recorded and categorized appropriately so that the business’s financial reports accurately reflect its activity.


    Reconciling Bank and Credit Card Accounts

    Reconciliation involves comparing the transactions in the accounting system with the actual activity shown on bank and credit card statements.

    This helps identify:

    • Missing transactions
    • Duplicate transactions
    • Incorrect amounts
    • Incorrect classifications
    • Other discrepancies

    Regular reconciliations are an important part of maintaining reliable books.


    Managing Accounts Receivable

    Accounts receivable represents money customers owe the business.

    A bookkeeper may help track:

    • Customer invoices
    • Payments received
    • Outstanding balances
    • Overdue invoices
    • Unapplied payments

    For a service business, keeping track of what customers owe can be particularly important for maintaining healthy cash flow.

    Managing Accounts Payable

    Accounts payable is essentially the other side of the equation: money the business owes to vendors and suppliers.

    A bookkeeper may track:

    • Vendor bills
    • Payment dates
    • Outstanding balances
    • Vendor payments

    This gives the business owner better visibility into upcoming obligations.


    Preparing Financial Reports

    A bookkeeper may also prepare routine financial reports such as:

    • Profit & Loss statements
    • Balance Sheets
    • Accounts receivable reports
    • Accounts payable reports
    • Other management reports

    These reports provide the financial information that can later be analyzed for planning and decision-making.


    What Does an Accountant Do?

    Now let’s look at the other side of bookkeeping vs. accounting.

    Accountants generally work with financial information at a higher analytical level, although exact responsibilities vary by accountant and firm.

    An accountant may use the financial records maintained through bookkeeping to perform work such as:

    Tax Preparation

    An accountant may prepare federal, state, or local tax returns, depending on their services and qualifications.

    Tax Planning

    An accountant may help a business consider strategies for managing its tax obligations.

    Financial Analysis

    Accountants can analyze financial statements and financial trends to help business owners better understand performance.

    Budgeting and Forecasting

    Accounting professionals may help businesses develop budgets, forecasts, and financial projections.

    Business Advisory

    Some accountants provide advisory services that help owners evaluate financial decisions and plan for growth.

    The important point is that accounting generally builds on financial information that must first be recorded accurately.

    If the underlying records are incomplete or inaccurate, the analysis built on them may also be affected.


    Bookkeeper vs. Accountant: Side-by-Side

    One of the easiest ways to understand bookkeeping vs. accounting is to compare their typical responsibilities.

    AreaBookkeeperAccountant
    Record transactions✅ Primary responsibilityMay review
    Categorize transactionsMay review
    Bank reconciliationMay review
    Credit card reconciliationMay review
    Accounts receivableMay review
    Accounts payableMay review
    Routine financial reports✅ Often prepares✅ Reviews/analyzes
    Financial analysisLimited/routine
    Tax preparationGenerally not primary role
    Tax planningGenerally not primary role
    Budgeting/forecastingMay provide information✅ Often provides
    Business advisoryLimitedOften offered

    An important caveat

    These responsibilities aren’t universal.

    Some bookkeepers offer additional financial services.

    Some accountants provide extensive bookkeeping.

    Some firms offer both.

    So when choosing a professional, don’t rely solely on their job title.

    Look at the actual services they provide and whether they have the appropriate expertise for the work you need.


    How Bookkeeping and Accounting Work Together

    This is where bookkeeping vs. accounting becomes less about choosing one and more about understanding how the two functions connect.

    Think of the process like this:

    Business transactions

    Bookkeeping

    Accurate, organized financial records

    Accounting

    Analysis, reporting, planning, and tax work

    Better-informed business decisions

    A bookkeeper helps make sure the financial information is captured and organized.

    An accountant can then use that information for higher-level financial work.

    That’s why the two functions are often complementary rather than competing.


    What Does This Look Like for an HVAC Business?

    Let’s use a real-world example.

    Imagine you own an HVAC company.

    Your technicians are completing service calls and installations every day.

    Your business may have:

    • Customer invoices
    • Customer payments
    • Parts purchases
    • Equipment purchases
    • Fuel expenses
    • Service vehicles
    • Payroll
    • Vendor bills
    • Credit card transactions
    • Bank transactions

    The bookkeeping side

    Your bookkeeper may record and categorize those transactions, reconcile your accounts, track outstanding invoices, manage vendor bills, and prepare monthly financial reports.

    The accounting side

    Your accountant may use those records for tax preparation, tax planning, financial analysis, forecasting, or other advisory work.

    This illustrates the relationship clearly.

    The bookkeeper helps ensure the financial data is organized and current.

    The accountant can then use that information for higher-level financial work.

    For a growing HVAC business, having both functions working properly can provide a much stronger financial foundation.


    Do I Need a Bookkeeper, an Accountant, or Both?

    This is probably the question most small-business owners really want answered.

    The answer depends on your business.

    You May Primarily Need Bookkeeping Support If:

    Your books aren’t being maintained consistently.

    Your bank accounts aren’t reconciled.

    Your books are months behind.

    Your accounts receivable isn’t current.

    Your vendor bills aren’t being tracked properly.

    You need reliable monthly financial reports.

    You’re spending too much time trying to keep up with QuickBooks.

    In these situations, getting the bookkeeping foundation in order may be your first priority.


    You May Need Accounting Support If:

    You need tax preparation.

    You need tax planning.

    You need more advanced financial analysis.

    You’re preparing financial projections.

    You’re considering a major business transaction.

    You need specialized financial or tax advice.

    In these situations, an accountant may be the appropriate professional to consult.


    Many Businesses Benefit From Both

    It’s not necessarily an either-or decision.

    A small business can have a bookkeeper maintaining its day-to-day financial records while an accountant handles tax and higher-level financial work.

    This arrangement can actually make everyone’s job easier.

    The bookkeeper keeps the records organized and current.

    The accountant receives better-quality information to work with.

    And the business owner gets a clearer financial picture.

    That’s one of the biggest practical benefits of understanding bookkeeping vs. accounting.


    Can One Person Do Both?

    Yes.

    In some small businesses, one professional may provide both bookkeeping and accounting services.

    That’s perfectly possible.

    However, the important question isn’t simply:

    “What is this person’s title?”

    Instead, ask:

    “Does this person have the skills and qualifications needed for the specific work I need?”

    Someone may be excellent at bookkeeping but not provide tax services.

    Another professional may offer both bookkeeping and accounting.

    Another may focus primarily on tax and advisory work.

    The services and qualifications matter more than the label.


    When Should You Hire a Bookkeeper?

    Understanding bookkeeping vs. accounting can also help you recognize when it’s time to bring in professional bookkeeping support.

    Consider getting help if:

    You’re spending too much time on your books.

    If bookkeeping is taking evenings or weekends away from running your business, your time may be better spent elsewhere.

    Your books are consistently behind.

    If your financial records are weeks or months behind, you may be operating without reliable current information.

    Your financial reports don’t make sense.

    If you’re constantly questioning whether your numbers are correct, your bookkeeping system may need attention.

    Your business is becoming more complex.

    More employees, customers, vendors, vehicles, bank accounts, credit cards, and transactions create additional bookkeeping responsibilities.

    You’re making decisions without reliable financial information.

    If you don’t trust your numbers when deciding whether to hire, expand, purchase equipment, or change pricing, it’s worth addressing the underlying financial records.

    For a deeper look at these signs, see:

    5 Signs It’s Time to Hire a Bookkeeper

    Why the Difference Matters for Your Business

    You might be wondering:

    “Why do I even need to know the difference?”

    Because hiring the right professional starts with understanding what problem you’re actually trying to solve.

    If your problem is:

    “My books haven’t been reconciled in four months.”

    You may need bookkeeping help.

    If your problem is:

    “I need help preparing my business tax return.”

    You may need an accountant.

    If your problem is:

    “I want to know whether I can afford to expand to another location.”

    You may need accounting or advisory support.

    And sometimes, you need all three levels of support at different stages.

    Understanding bookkeeping vs. accounting helps you ask better questions and find the right resource.

    How Prime Ledger Fits Into Your Financial Team

    At Prime Ledger Bookkeeping, our role is focused on the bookkeeping side of the financial process.

    We help HVAC and service-based businesses maintain accurate, organized, and up-to-date financial records.

    Our services include:

    • Monthly bookkeeping
    • Bank and credit card reconciliations
    • Accounts receivable
    • Accounts payable
    • Financial reporting
    • Bookkeeping cleanup and catch-up
    • QuickBooks Online support

    We don’t believe your bookkeeper has to replace your accountant.

    In fact, we believe the opposite.

    A good bookkeeper can be a valuable partner to your CPA or accountant.

    When your financial records are organized and current, your accountant has better information to work with.

    And you, as the business owner, have greater visibility into your financial position.

    That’s the goal:

    Accurate Books. Clear Decisions. Peace of Mind.


    📚 Key Takeaways

    The simplest way to remember bookkeeping vs. accounting is:

    Bookkeeping records and organizes financial transactions.

    Accounting analyzes and interprets that financial information for higher-level financial work.

    Remember:

    ✅ Bookkeepers help maintain accurate financial records.

    ✅ Accountants may use those records for tax, analysis, planning, and advisory work.

    ✅ The two functions often overlap, depending on the professional or firm.

    ✅ A business may benefit from both a bookkeeper and an accountant.

    ✅ Your specific needs—not someone’s job title—should determine which professional you hire.

    Most importantly, good accounting depends on reliable financial information.

    And reliable financial information starts with good bookkeeping.


    Frequently Asked Questions

    What’s the difference between bookkeeping and accounting?

    Bookkeeping primarily focuses on recording, categorizing, and organizing financial transactions. Accounting generally involves analyzing and interpreting financial information for purposes such as tax preparation, planning, forecasting, reporting, and decision-making.

    Is bookkeeping part of accounting?

    Bookkeeping and accounting are closely related, but they aren’t exactly the same function. Bookkeeping focuses primarily on maintaining financial records, while accounting generally uses those records for analysis and higher-level financial work.

    Do I need a bookkeeper if I have an accountant?

    Possibly. Some accountants provide bookkeeping services, while others focus primarily on tax, analysis, and advisory work. If your accountant doesn’t maintain your day-to-day books, a bookkeeper can help keep the records organized and current.

    Can a bookkeeper prepare financial statements?

    A bookkeeper may prepare routine financial statements and management reports, depending on their services and expertise. More complex financial statement work may involve an accountant.

    Can a bookkeeper do my taxes?

    Tax preparation is generally considered an accounting or tax professional function rather than the primary role of a bookkeeper. However, individual professionals may offer different combinations of services. Always confirm that the professional you hire is qualified for the specific tax work you need.

    Should a small business have both a bookkeeper and an accountant?

    Many small businesses can benefit from both. A bookkeeper can maintain accurate day-to-day records while an accountant handles tax preparation, tax planning, financial analysis, or advisory work.

    Is a bookkeeper cheaper than an accountant?

    Generally, bookkeeping and accounting services have different pricing structures based on the scope and complexity of the work. The better comparison is to evaluate what services you actually need rather than choosing solely based on the professional’s title or hourly rate.

    Conclusion

    The difference between bookkeeping and accounting becomes much easier to understand when you think about the roles they play.

    Bookkeeping keeps the financial records organized.

    Accounting helps turn those records into useful financial information.

    Neither function is necessarily more important than the other.

    They simply serve different purposes.

    For a small HVAC or service-based business, reliable bookkeeping can provide the foundation your accountant needs for tax work, analysis, planning, and other financial services.

    And for you as the business owner, it provides something equally important:

    A clearer understanding of what’s happening inside your business.

    So if you’ve been wondering about bookkeeping vs. accounting, remember:

    Good bookkeeping gives you accurate information. Good accounting helps you understand and use it.

    And together, they can give you the financial foundation you need to run your business with greater confidence.


    Not Sure What Financial Support Your Business Needs?

    You don’t have to figure it out alone.

    Prime Ledger Bookkeeping helps HVAC and service-based businesses maintain accurate, organized financial records through reliable monthly bookkeeping, reconciliations, accounts receivable and payable support, and financial reporting.

    If you’re unsure whether your business needs bookkeeping support—or how bookkeeping can work alongside your existing accountant—we’d be happy to discuss your situation.

    Schedule a free bookkeeping consultation.

    Let’s determine what your business needs and how we can help.

    Accurate Books. Clear Decisions. Peace of Mind.


    Related Articles

    📚 Bookkeeping Basics Monday

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    A beginner-friendly guide to the responsibilities and value of a professional bookkeeper.

    🔧 Fix-It Wednesday

    Your Books Are Months Behind—Now What?

    A practical guide to catching up your bookkeeping and getting your financial records back on track.

    📈 Finance Friday

    5 Signs It’s Time to Hire a Bookkeeper

    Five practical signs that your business may have outgrown DIY bookkeeping.

  • 5 Signs It’s Time to Hire a Bookkeeper

    5 Signs It’s Time to Hire a Bookkeeper

    Your Business Is Growing. Is Your Bookkeeping Keeping Up?

    When you started your business, doing your own bookkeeping probably made sense.

    There weren’t many transactions.

    You had only a handful of customers.

    Maybe you had one bank account and one business credit card.

    Keeping your books current didn’t take much time.

    But businesses change.

    You add employees.

    You take on more customers.

    You send more invoices.

    You purchase more supplies.

    You add vehicles.

    You work with more vendors.

    And suddenly, the bookkeeping that once took an hour or two a month starts taking an entire weekend.

    Maybe you’ve even reached the point where you avoid opening QuickBooks because you already know there’s a backlog waiting for you.

    So how do you know when it’s actually time to hire a bookkeeper?

    The answer isn’t simply “when bookkeeping becomes difficult.”

    The better question is:

    Is handling my bookkeeping myself still the best use of my time—and is my current system giving me financial information I can trust?

    For some businesses, doing their own bookkeeping is perfectly reasonable.

    For others, professional bookkeeping can save valuable time, improve financial visibility, and give the owner more confidence in important business decisions.

    In this guide, we’ll walk through five signs that it may be time to hire a bookkeeper, including what those signs can look like for HVAC and other service-based businesses.


    Table of Contents

    1. You’re Spending Too Much Time on Your Books
    2. Your Books Are Always Behind
    3. Your Financial Reports Don’t Make Sense
    4. Your Business Is Becoming More Complex
    5. You’re Making Decisions Without Reliable Numbers
    6. What This Looks Like for an HVAC Business
    7. Do You Actually Need to Hire a Bookkeeper?
    8. Is a Bookkeeper an Expense or an Investment?
    9. How Prime Ledger Can Help
    10. Key Takeaways
    11. Frequently Asked Questions
    12. Conclusion

    1. You’re Spending Too Much Time on Your Books

    One of the clearest signs that it may be time to hire a bookkeeper is simple:

    Bookkeeping is taking too much of your time.

    If you’re wondering whether it’s time to hire a bookkeeper, that question itself may be a sign that your business has outgrown DIY bookkeeping.

    Think about what your time is worth as a business owner.

    You could be:

    • Talking to customers
    • Generating new business
    • Managing employees
    • Scheduling jobs
    • Improving operations
    • Building vendor relationships
    • Planning your next stage of growth

    Instead, you may be spending evenings categorizing transactions and weekends reconciling accounts.

    There’s nothing inherently wrong with doing your own bookkeeping.

    The question is whether it’s still the best use of your time.

    Your Time Has a Cost

    Suppose you’re spending eight hours every month on bookkeeping.

    That’s:

    96 hours a year.

    That’s the equivalent of more than two full 40-hour workweeks.

    Now ask yourself:

    What else could I accomplish with those 96 hours?

    Maybe you could spend more time generating sales.

    Maybe you could improve your operations.

    Maybe you could spend more time with your team.

    Maybe you could simply have some of your evenings and weekends back.

    The point isn’t that every business owner should outsource bookkeeping immediately.

    It’s that your time has value, and bookkeeping should be evaluated alongside everything else competing for that time.


    2. Your Books Are Always Behind

    Another major warning sign is that your bookkeeping is consistently late.

    Maybe you’re a month behind.

    Then two months.

    Then suddenly you realize you haven’t reconciled your accounts in six months.

    This creates a bigger problem than just having unfinished administrative work.

    You lose financial visibility.

    When your books aren’t current, your financial reports aren’t giving you a reliable picture of what’s happening today.

    You may not know:

    • How profitable you are
    • What your cash flow looks like
    • Who owes you money
    • What bills are outstanding
    • Whether expenses are increasing
    • Whether you’re actually on track with your goals

    This is especially important for growing service businesses.

    If you’re busy completing jobs but your financial records are months behind, you’re essentially running part of your business using outdated information.

    When bookkeeping consistently falls behind, it may be time to hire a bookkeeper who can keep your records current while you focus on running the business.

    Being Behind Doesn’t Mean Your Business Is Failing

    It’s worth emphasizing this.

    A bookkeeping backlog doesn’t automatically mean your business is poorly managed.

    It can happen because you’re busy.

    For example, an HVAC owner may spend weeks managing:

    • Emergency service calls
    • Installations
    • Technicians
    • Customer issues
    • Parts
    • Equipment
    • Vendors

    Bookkeeping gets pushed to the bottom of the list.

    The problem begins when “I’ll catch up later” becomes a recurring system.

    If you’re repeatedly falling behind, professional bookkeeping may be worth considering.


    3. Your Financial Reports Don’t Make Sense

    This is another important sign.

    You open your Profit & Loss Statement and think:

    “That doesn’t look right.”

    Maybe revenue seems too high.

    Maybe expenses are in strange categories.

    Maybe there are negative balances you don’t understand.

    Maybe your bank balance doesn’t seem to match what your books are telling you.

    Financial reports are supposed to provide clarity.

    If you’re spending time trying to figure out whether your reports are accurate instead of using them to make decisions, there’s a problem somewhere in the bookkeeping process.


    Your Reports Should Answer Questions

    A useful set of financial reports should help you answer questions such as:

    Are we profitable?

    Where is our money going?

    Which expenses are increasing?

    How much do customers owe us?

    What do we owe our vendors?

    How has the business performed compared with previous periods?

    You don’t need to be an accountant to benefit from your financial reports.

    But your underlying bookkeeping needs to be accurate enough for those reports to mean something.


    4. Your Business Is Becoming More Complex

    Growth is exciting.

    But growth also creates financial complexity.

    Think about a business that started with:

    1 owner → 1 bank account → 1 credit card → a few customers

    Now imagine that same business three years later:

    8 employees → multiple accounts → several credit cards → dozens of vendors → hundreds of customer transactions

    The bookkeeping requirements have changed dramatically.

    More Customers Mean More Transactions

    Every new customer can potentially create:

    • Invoices
    • Payments
    • Refunds
    • Deposits
    • Adjustments
    • Outstanding balances

    More activity means more bookkeeping work.

    More Employees Mean More Complexity

    Payroll creates additional financial activity and recordkeeping requirements.

    As your team grows, your financial records need to keep up.

    More Vendors Mean More Bills

    Service businesses often purchase materials, parts, fuel, equipment, and other supplies.

    As operations expand, accounts payable becomes more important.

    More Accounts Mean More Reconciliations

    A growing business may eventually have:

    • Multiple bank accounts
    • Credit cards
    • Loans
    • Payment processors
    • Financing accounts

    Each one creates additional bookkeeping responsibilities.

    At some point, what worked when your business was small may simply stop working.


    5. You’re Making Decisions Without Reliable Numbers

    This may be the most important sign of all.

    Business owners make financial decisions constantly.

    Should you:

    Hire another technician?

    Purchase another service vehicle?

    Invest in new equipment?

    Raise your prices?

    Expand into another market?

    Take on a larger project?

    These decisions can have significant financial consequences.

    And yet, many business owners make them without having current, reliable financial information.

    That’s risky.

    Your Books Should Help You Decide

    Good bookkeeping doesn’t make the decision for you.

    It gives you better information with which to make the decision.

    For example:

    Instead of asking:

    “Can we afford another technician?”

    you can look at your current revenue, expenses, cash flow, and profitability and ask:

    “Based on our current financial position, what would adding another technician do to the business?”

    That’s a much better question.

    And it starts with accurate books.


    What This Looks Like for an HVAC Business

    Let’s put these five signs into a real-world example.

    Imagine an HVAC company that started with the owner and one technician.

    At first, the owner handled everything.

    Customer calls.

    Service appointments.

    Invoices.

    Vendor bills.

    Bank transactions.

    Bookkeeping.

    It worked.

    Three years later, the company has eight technicians, several service vehicles, dozens of vendors, recurring maintenance customers, and hundreds of transactions every month.

    The owner is still trying to do all the bookkeeping personally.

    What happens?

    The books begin falling behind.

    Bank reconciliations aren’t completed consistently.

    Customer invoices aren’t reviewed as often.

    Vendor bills accumulate.

    Financial reports aren’t reviewed monthly.

    And the owner starts making decisions based primarily on the bank balance.

    The business may be doing well operationally.

    But financially, the owner has lost visibility.

    That’s a strong signal that the bookkeeping system needs to change.

    The answer isn’t necessarily to hire the first bookkeeper you find.

    The answer is to recognize that the business has outgrown the old system.


    Do You Actually Need to Hire a Bookkeeper?

    Here’s something worth saying clearly:

    Not every business needs a bookkeeper immediately.

    If your business is small, your transactions are limited, your books are current, and you have the time and knowledge to maintain them accurately, DIY bookkeeping may work perfectly well.

    But professional bookkeeping may become valuable when one or more of these conditions appear:

    Your time is becoming more valuable.

    Your transaction volume is increasing.

    Your books are consistently behind.

    Your financial reports aren’t reliable.

    Your business is becoming more complex.

    You need better financial visibility to make decisions.

    When several of these happen at the same time, it’s probably worth exploring professional bookkeeping support.


    Is a Bookkeeper an Expense or an Investment?

    This is one of the most important questions business owners should ask.

    Hiring a bookkeeper is an expense.

    But it can also be an investment in your business’s time, organization, and financial visibility.

    Consider the potential value of getting your time back.

    If bookkeeping takes eight hours a month, that’s 96 hours per year.

    What could you do with those hours?

    More sales?

    More customer relationships?

    Better operations?

    Employee development?

    Business planning?

    Or simply more time away from work?

    There is no universal answer because every business owner’s time has a different value.

    That’s why the decision shouldn’t be:

    “Can I afford a bookkeeper?”

    It should also be:

    “What is it costing my business for me to continue doing this myself?”


    How Prime Ledger Can Help

    At Prime Ledger Bookkeeping, we help HVAC and service-based businesses maintain accurate, organized financial records without requiring the business owner to manage every bookkeeping task themselves.

    Our services include:

    • Monthly bookkeeping
    • Bank and credit card reconciliations
    • Accounts receivable
    • Accounts payable
    • Financial reporting
    • Bookkeeping cleanup and catch-up
    • QuickBooks Online support

    Our goal is not simply to take bookkeeping off your to-do list.

    It’s to help you have financial information you can actually use.

    Because when your books are accurate and current, you can make decisions with greater confidence.

    Accurate Books. Clear Decisions. Peace of Mind.


    📈 Key Takeaways

    It may be time to hire a bookkeeper if:

    Bookkeeping is taking too much of your time.

    Your books are consistently behind.

    Your financial reports don’t make sense.

    Your business has become significantly more complex.

    You’re making important decisions without reliable financial information.

    You don’t necessarily need to outsource your bookkeeping simply because you own a business.

    But when bookkeeping begins taking valuable time away from running the business—or when your financial information becomes unreliable—professional support may be worth considering.


    Frequently Asked Questions

    When should a small business hire a bookkeeper?

    A small business should consider hiring a bookkeeper when bookkeeping becomes too time-consuming, the books consistently fall behind, financial transactions become more complex, or the owner needs reliable financial reports to make business decisions.

    Is it worth hiring a bookkeeper for a small business?

    It can be, particularly when the time required to maintain the books becomes significant or the business needs more reliable financial information. The decision should consider both the cost of bookkeeping and the value of the owner’s time and financial visibility.

    Can I do my own bookkeeping?

    Yes. Many small businesses handle their own bookkeeping, especially when transaction volume is low and the owner has the necessary time and knowledge. As the business grows, however, professional bookkeeping may become more practical.

    What does a bookkeeper do for a small business?

    A bookkeeper can record and categorize transactions, reconcile bank and credit card accounts, manage accounts receivable and payable, maintain financial records, and prepare monthly financial reports.

    Should an HVAC business hire a bookkeeper?

    An HVAC business may benefit from professional bookkeeping as its transaction volume and operational complexity increase. Multiple technicians, service vehicles, vendors, customer invoices, equipment purchases, and other expenses can make bookkeeping increasingly time-consuming.

    How much does a bookkeeper cost?

    Bookkeeping costs vary based on factors such as transaction volume, number of accounts, services required, business complexity, and frequency of bookkeeping. The right comparison isn’t simply the monthly fee—it should also consider the value of accurate financial information and the owner’s time.


    Conclusion

    There isn’t a magic revenue number or employee count that means every business suddenly needs a bookkeeper.

    The better indicator is complexity and opportunity cost.

    If you’re spending too much time maintaining your books, falling behind, struggling to understand your financial reports, managing a rapidly growing business, or making decisions without numbers you trust, it may be time to consider professional bookkeeping.

    For an HVAC or service-based business, that decision can become particularly important as the business grows.

    You started your business to build something valuable—not to spend every evening categorizing transactions.

    The goal isn’t to outsource everything.

    The goal is to make sure your time and financial systems are supporting the business you’re trying to build.

    When your books are accurate, your decisions can be clearer.

    And when your decisions are clearer, you can move your business forward with greater confidence.


    Is It Time to Hand Off Your Bookkeeping?

    If you’re spending too much time on your books—or you’re no longer confident in the financial information you’re using to run your business—let’s talk.

    Prime Ledger Bookkeeping helps HVAC and service-based businesses maintain accurate books, understand their financial performance, and spend less time managing bookkeeping.

    Schedule a free bookkeeping consultation today.

    We’ll help you understand where your bookkeeping stands and whether professional bookkeeping is the right fit for your business.

    Accurate Books. Clear Decisions. Peace of Mind.


    Related Articles

    📚 Bookkeeping Basics Monday

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    Learn what professional bookkeeping involves and why accurate financial records matter.

    🔧 Fix-It Wednesday

    Your Books Are Months Behind—Now What?

    A practical guide to catching up your bookkeeping and getting your financial records back on track.

  • Your Books Are Months Behind—Now What?

    Your Books Are Months Behind—Now What?

    Your Books Are Behind. Don’t Panic.

    It’s been a busy few months.

    Customers needed you. Jobs needed to get done. Your team needed you. Vendors needed to be paid. And somewhere along the way, your bookkeeping fell further and further behind.

    Maybe it’s been two months.

    Maybe six.

    Maybe you don’t even want to check.

    If that sounds familiar, you’re not alone.

    For many small business owners—especially owners of busy HVAC, plumbing, electrical, landscaping, and other service-based businesses—bookkeeping is something that gets pushed aside when there’s more immediate work demanding attention.

    The problem is that the longer your books stay behind, the harder it becomes to know what’s actually happening financially.

    You may be making sales without knowing your true profitability.

    You may have customers who haven’t paid their invoices.

    You may have vendor bills that haven’t been recorded.

    And you may be making important business decisions based on financial information that’s months old.

    The good news? Being behind doesn’t mean your books can’t be fixed.

    You don’t need to panic, and you don’t necessarily need to start entering transactions randomly just to get caught up.

    You need a systematic process.

    In this guide, we’ll walk through how to catch up bookkeeping, what to prioritize, when professional help makes sense, and how to keep your books from falling behind again.

    Table of Contents

    • First, Don’t Panic
    • What Happens When Your Books Fall Months Behind?
    • Step-by-Step: How to Catch Up Your Bookkeeping
    • What Catch-Up Bookkeeping Looks Like for an HVAC Business
    • Should You Catch Up Your Books Yourself or Hire a Bookkeeper?
    • How to Keep Your Books From Falling Behind Again
    • How Prime Ledger Can Help
    • Key Takeaways
    • Frequently Asked Questions
    • Conclusion

    First, Don’t Panic

    Being behind on your bookkeeping can feel overwhelming, especially when you don’t know how much work is waiting for you.

    But the first step is surprisingly simple:

    Stop making the problem bigger.

    If your books are three months behind, don’t let them become four months behind while you’re trying to figure out how to fix the first three.

    Start by establishing where you are today.

    Then work backward systematically.

    Being Behind Doesn’t Mean Your Business Is Failing

    A bookkeeping backlog doesn’t necessarily mean your business is poorly managed.

    In fact, it can happen because your business is growing.

    An HVAC owner may spend an entire week managing emergency calls.

    A plumbing company may have technicians working overtime.

    An electrical contractor may be juggling several large projects.

    When you’re busy serving customers, bookkeeping can easily fall to the bottom of the list.

    The important thing is to recognize the problem and address it.

    The Bigger Risk Is Continuing to Ignore It

    The real danger isn’t necessarily that your books are already behind.

    It’s continuing to operate without reliable financial information.

    The longer the backlog grows, the harder it becomes to answer basic questions:

    How profitable are we?

    How much cash do we really have available?

    Who still owes us money?

    What bills do we owe?

    Which expenses are increasing?

    Can we afford to hire another employee?

    When your books are months behind, those answers become much harder to trust.

    What Happens When Your Books Fall Months Behind?

    A bookkeeping backlog affects more than your accounting software.

    It can affect how you run your business.

    You Lose Financial Visibility

    If your books haven’t been updated in months, your Profit & Loss Statement may not reflect your current situation.

    You might be looking at financial information from several months ago while making decisions about today.


    Cash Flow Becomes Harder to Manage

    Your bank balance tells you how much cash is in your account.

    It doesn’t necessarily tell you what cash you need to reserve for upcoming bills, payroll, or other obligations.

    Without current records, cash flow planning becomes much more difficult.


    Outstanding Customer Payments Can Be Missed

    If accounts receivable isn’t current, you may not have a reliable list of customers who still owe your business money.

    That can result in delayed follow-up and slower cash collection.


    Vendor Bills Can Fall Through the Cracks

    The same problem can happen with accounts payable.

    If bills aren’t properly recorded and tracked, you may lose visibility into what your business owes and when payments are due.


    Tax Preparation Becomes More Difficult

    When financial records aren’t current, tax preparation can require additional cleanup before your tax professional can confidently use the information.

    Keeping your books current throughout the year can make that process much smoother.

    Step-by-Step: How to Catch Up Your Bookkeeping

    Now let’s get to the part you’ve been waiting for.

    How do you actually catch up?

    The key is to work systematically instead of trying to fix everything at once.


    Step 1: Stop the Backlog From Growing

    Before you start cleaning up old transactions, make sure new transactions aren’t continuing to pile up.

    Establish a cutoff date.

    For example:

    “Today is August 10. From this point forward, I’m keeping new transactions current while I work backward through the backlog.”

    This prevents you from constantly chasing a moving target.


    Step 2: Gather Your Financial Records

    You’ll need the information necessary to reconstruct the missing periods.

    Depending on your business, that may include:

    • Bank statements
    • Credit card statements
    • Loan statements
    • Customer invoices
    • Vendor bills
    • Sales records
    • Receipts
    • Payroll records
    • Payment processor reports
    • Equipment purchase records

    Don’t worry about organizing everything perfectly at first.

    The goal is to gather the complete source information.


    Step 3: Review Your Accounting Setup

    Before entering months of transactions, take a moment to make sure your accounting system is set up properly.

    Review your:

    • Chart of Accounts
    • Bank and credit card accounts
    • Customer accounts
    • Vendor accounts
    • Income categories
    • Expense categories

    If the underlying structure is wrong, you can spend hours cleaning up transactions only to create more work later.


    Step 4: Work Through Your Bank Accounts

    Start with your oldest unreconciled period and work forward.

    Compare your accounting records against your actual bank statements.

    Look for:

    • Missing transactions
    • Duplicate transactions
    • Incorrect amounts
    • Incorrect dates
    • Unclear transactions
    • Transactions recorded in the wrong account

    Don’t simply mark everything as reconciled to make the problem disappear.

    The goal is to make the books accurate.


    Step 5: Review Uncategorized Transactions

    Once transactions are recorded, look for items sitting in:

    • Uncategorized income
    • Uncategorized expenses
    • Suspense accounts
    • Other temporary categories

    These items deserve attention because they may affect your financial reports.

    If you’re unsure how a transaction should be treated, don’t guess.


    Step 6: Catch Up Accounts Receivable

    Now determine what customers owe your business.

    Review:

    • Outstanding invoices
    • Customer payments
    • Overdue balances
    • Unapplied payments
    • Credit memos, if applicable

    For an HVAC company, this might mean reviewing months of service calls and installations to determine which invoices have been paid and which remain outstanding.


    Step 7: Catch Up Accounts Payable

    Next, review what your business owes.

    Look at:

    • Vendor bills
    • Outstanding balances
    • Payment history
    • Unrecorded bills
    • Duplicate bills

    This gives you a much clearer picture of your current obligations.


    Step 8: Review Your Financial Reports

    Once the books are caught up and reconciled, run your financial reports.

    At minimum, review:

    Profit & Loss Statement

    Understand your revenue, expenses, and profitability.

    Balance Sheet

    Review your assets, liabilities, and equity.

    Cash Flow Information

    Understand how cash has moved through the business.

    Don’t just generate the reports.

    Look at them.

    Ask questions.

    Does the revenue look reasonable?

    Are expenses unusually high?

    Are there negative balances that shouldn’t be there?

    Does the information make sense compared with what actually happened in the business?

    What Catch-Up Bookkeeping Looks Like for an HVAC Business

    Let’s make this real.

    Imagine an HVAC company has been extremely busy for the last six months.

    The owner has been focused on:

    • Emergency service calls
    • New installations
    • Technician schedules
    • Customer complaints
    • Parts
    • Equipment
    • Payroll
    • Vendor relationships

    Bookkeeping kept getting pushed back.

    Now six months have passed.

    The owner opens QuickBooks and realizes the books haven’t been properly reconciled since February.

    What needs to be reviewed?

    Potentially:

    Revenue

    Service calls, maintenance agreements, installations, and other customer payments.

    Accounts Receivable

    Which customers have unpaid invoices?

    Parts and Materials

    How much is being spent on supplies and replacement parts?

    Vehicles

    What expenses are associated with service vehicles?

    Fuel

    How much is being spent on fuel?

    Vendors

    Which supplier bills remain unpaid?

    Payroll

    Are payroll-related transactions properly recorded?

    Credit Cards

    Have all business purchases been captured and categorized?

    This is why catch-up bookkeeping isn’t simply about entering six months of transactions.

    It’s about making sure the financial records tell an accurate story of what happened during those six months.

    Should You Catch Up Your Books Yourself or Hire a Bookkeeper?

    The answer depends on the complexity of your books and how far behind you are.

    DIY May Make Sense If:

    • You’re only slightly behind.
    • Your transaction volume is relatively low.
    • Your accounts are already properly connected.
    • Your reconciliations are straightforward.
    • Your accounting setup is organized.
    • You understand your bookkeeping system.

    If that’s your situation, a focused cleanup project may be manageable.


    Professional Help May Make More Sense If:

    You’re several months behind.

    You have multiple bank and credit card accounts.

    Your reconciliations haven’t been completed.

    Your financial reports don’t make sense.

    You have a large number of uncategorized transactions.

    Accounts receivable or payable are unclear.

    Your business has grown significantly.

    Or you simply don’t have the time to do the cleanup correctly.

    In those situations, trying to fix everything yourself may cost more in time and frustration than getting professional help.

    How to Keep Your Books From Falling Behind Again

    Getting caught up is only half the solution.

    The real goal is to stay caught up.

    Establish a Monthly Bookkeeping Routine

    At the end of each month:

    1. Record transactions.
    2. Reconcile bank accounts.
    3. Reconcile credit cards.
    4. Review accounts receivable.
    5. Review accounts payable.
    6. Review financial reports.
    7. Address unusual or unexplained transactions.

    The exact process will vary depending on the business, but the principle is simple:

    Don’t let months of bookkeeping pile up again.


    Set a Financial Review Date

    Choose one day each month to review your financial reports.

    It doesn’t have to take all day.

    The goal is simply to create a regular habit of looking at your numbers.

    Because financial information is most useful when it’s current.

    How Prime Ledger Can Help

    If your books are months behind, you don’t necessarily need to figure everything out alone.

    At Prime Ledger Bookkeeping, we help HVAC and service-based businesses get their financial records organized and establish a reliable monthly bookkeeping process.

    Our services include:

    • Bookkeeping cleanup and catch-up
    • Monthly bookkeeping
    • Bank and credit card reconciliations
    • Accounts receivable
    • Accounts payable
    • Monthly financial reporting
    • QuickBooks Online support

    Our goal isn’t simply to get your books caught up.

    It’s to help you establish a system that keeps them current.

    Because once your books are accurate, you can start using your financial information to make better decisions.

    Accurate Books. Clear Decisions. Peace of Mind.

    🔧 Key Takeaways

    If your books are months behind, remember:

    Don’t panic. A bookkeeping backlog can be fixed.

    Stop the backlog from growing while you work through the older periods.

    Gather complete financial records before beginning the cleanup.

    Reconcile accounts carefully instead of simply marking them complete.

    Review accounts receivable and payable so you know what you’re owed and what you owe.

    Review your financial reports once the cleanup is complete.

    Establish a monthly routine so your books don’t fall behind again.

    And if the backlog is extensive or complicated, professional help may save you significant time and reduce the risk of costly errors.

    Frequently Asked Questions

    How do I catch up bookkeeping that is months behind?

    Start by stopping the backlog from growing, gathering your financial records, reviewing your accounting setup, and working through your oldest unreconciled period forward. Reconcile your accounts, review outstanding receivables and payables, and verify your financial reports once the cleanup is complete.


    How long does it take to catch up bookkeeping?

    It depends on how many months are behind, the number of transactions, the number of accounts, and how much cleanup is required. A small business with a few accounts may catch up relatively quickly, while a larger or more complex business can require significantly more work.


    Can a bookkeeper catch up my old books?

    Yes. A professional bookkeeper can help reconstruct missing records, reconcile accounts, correct bookkeeping issues, and bring financial records up to date. The amount of work depends on the condition and complexity of the existing records.


    Should I clean up QuickBooks before hiring a bookkeeper?

    Not necessarily. If you’re unsure what is wrong with your QuickBooks file, attempting a major cleanup yourself can sometimes create additional issues. A professional can assess the current condition of the books and determine what needs to be corrected.


    What records do I need to catch up my bookkeeping?

    Depending on your business, you may need bank and credit card statements, invoices, bills, receipts, payroll records, loan statements, payment processor reports, and other financial records.


    How can I prevent my books from falling behind again?

    Establish a consistent monthly bookkeeping routine. Regular transaction recording, account reconciliations, accounts receivable and payable reviews, and monthly financial reporting can help keep your records current.

    Conclusion

    Having months of bookkeeping sitting unfinished can feel overwhelming.

    But being behind doesn’t mean you’re stuck.

    The key is to stop the backlog from growing, gather your records, work through the missing periods systematically, reconcile your accounts, and verify that your financial reports accurately reflect your business.

    And once you’re caught up, don’t stop there.

    Put a monthly process in place so your books stay current.

    Because bookkeeping isn’t just about getting transactions recorded.

    It’s about having financial information you can trust when you need to make important decisions.

    If you’re an HVAC or service-based business owner whose books have fallen behind, getting them back on track can be one of the most valuable steps you take for your business’s financial health.

    🔧 Ready to Get Your Books Back on Track?

    If your bookkeeping is months behind, you don’t have to figure out the cleanup alone.

    Prime Ledger Bookkeeping helps HVAC and service-based businesses catch up their books, organize their financial records, and establish reliable monthly bookkeeping systems.

    Let’s figure out where your books stand and what it will take to get them current.

    Schedule your free bookkeeping consultation today.

    Accurate Books. Clear Decisions. Peace of Mind.

    Related Articles

    📚 Bookkeeping Basics Monday

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners?
    Our foundational guide explaining what professional bookkeeping involves and why it matters.

  • What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    What Does a Bookkeeper Do? A Complete Guide for Small Business Owners

    Behind Every Successful Business Is a Clear Financial Picture

    As a business owner, you probably spend most of your day serving customers, managing employees, scheduling jobs, ordering materials, answering calls, and finding new business. Somewhere between all of that, you’re also expected to keep accurate financial records.

    That’s where many business owners begin to feel overwhelmed.

    Maybe you’re saving receipts in a shoebox, updating QuickBooks only when you have spare time, or wondering whether your bank balance actually reflects how your business is performing. If any of that sounds familiar, you’re not alone.

    Many small business owners ask the same question:

    “What exactly does a bookkeeper do?”

    It’s a great question because bookkeeping is often misunderstood.

    Some people think bookkeeping is simply entering numbers into accounting software. Others believe it’s only important during tax season. In reality, professional bookkeeping is one of the most valuable investments a growing business can make.

    Accurate bookkeeping provides the financial foundation that allows business owners to understand where their money is going, identify opportunities to improve profitability, make informed decisions, and prepare for future growth.

    For HVAC contractors, plumbers, electricians, landscapers, cleaning companies, and other service-based businesses, bookkeeping isn’t just about compliance—it’s about gaining confidence in your business.

    When your books are accurate, your financial reports become meaningful. When your financial reports are meaningful, your decisions become better.

    At Prime Ledger Bookkeeping, we believe every business owner deserves accurate books, clear decisions, and peace of mind.

    In this guide, you’ll learn exactly what a professional bookkeeper does, why bookkeeping matters, and how the right bookkeeping partner can help you spend less time managing paperwork and more time growing your business.

    What Is Bookkeeping?

    Bookkeeping is the systematic process of recording, organizing, and maintaining every financial transaction that occurs in your business.

    Every payment you receive from a customer…

    Every invoice you send…

    Every vendor bill you pay…

    Every credit card purchase…

    Every payroll transaction…

    Every bank deposit…

    All of these financial activities tell the story of your business. Bookkeeping ensures that story is complete, accurate, and easy to understand.

    Think of bookkeeping as the foundation of your company’s financial health.

    Just as a building needs a solid foundation before additional floors can be added, every successful business depends on accurate bookkeeping before meaningful financial decisions can be made.

    Without organized financial records, it’s difficult to answer important questions such as:

    • Is my business actually profitable?
    • Which services generate the highest profit?
    • Can I afford to hire another employee?
    • Am I charging enough for my services?
    • Why is my bank account lower than expected?
    • How much cash do I really have available?

    Professional bookkeeping transforms thousands of individual financial transactions into useful information that helps business owners make confident decisions.

    Instead of guessing, you know.

    Instead of hoping, you understand.

    That’s the real value of bookkeeping.

    Bookkeeping Is More Than Data Entry

    One of the biggest misconceptions about bookkeeping is that it’s simply entering numbers into QuickBooks.

    While recording transactions is certainly part of the process, professional bookkeeping involves much more.

    A skilled bookkeeper ensures transactions are properly categorized, reconciles accounts, identifies discrepancies, maintains organized financial records, prepares financial reports, and helps business owners understand the financial health of their company.

    In other words, bookkeeping turns financial data into meaningful business information.

    Why Accurate Bookkeeping Matters

    Imagine trying to drive across the country with a broken GPS.

    You might eventually reach your destination, but you’ll probably waste time, take wrong turns, and experience unnecessary stress along the way.

    Running a business without accurate bookkeeping is similar.

    When your financial records aren’t current, every major business decision becomes more difficult.

    Should you purchase new equipment?

    Can you afford another technician?

    Is your pricing still profitable?

    Should you expand into another service area?

    Accurate bookkeeping provides the information needed to answer these questions with confidence rather than guesswork.

    It also gives you something many business owners don’t realize they need: confidence.

    When your numbers are organized and up to date, you can make decisions based on facts instead of guesswork.

    What Does a Bookkeeper Do Every Month?

    Professional bookkeeping is an ongoing process—not a once-a-year task.

    Throughout each month, a bookkeeper performs a series of responsibilities designed to keep your financial records accurate, organized, and up to date.

    Let’s take a closer look.


    1. Record Financial Transactions

    Every financial transaction must be accurately recorded.

    This includes:

    • Customer payments
    • Sales income
    • Vendor bills
    • Business expenses
    • Credit card purchases
    • Bank deposits
    • Payroll transactions
    • Loan payments

    Each transaction is categorized correctly so your financial reports accurately reflect how your business is performing.

    For example, if your HVAC company purchases replacement compressors, refrigerant, or service vehicle parts, those expenses should be classified appropriately. Proper categorization makes your reports more meaningful and helps simplify tax preparation.


    2. Reconcile Bank and Credit Card Accounts

    Bank reconciliation is one of the most important monthly bookkeeping tasks.

    A bookkeeper compares your accounting records with your bank and credit card statements to verify that every transaction has been recorded correctly.

    This process helps identify:

    • Missing transactions
    • Duplicate entries
    • Bank errors
    • Incorrect categorization
    • Unauthorized charges

    Without regular reconciliations, small errors can accumulate over time and create much larger problems.


    3. Manage Accounts Receivable

    Getting paid is essential to maintaining healthy cash flow.

    Your bookkeeper tracks customer invoices, records incoming payments, and monitors outstanding balances.

    This allows business owners to quickly identify overdue invoices and follow up before cash flow becomes a problem.

    For service-based businesses that complete multiple jobs each week, organized accounts receivable helps ensure completed work turns into collected revenue.


    4. Manage Accounts Payable

    Just as important as collecting payments is paying vendors accurately and on time.

    A professional bookkeeper organizes incoming bills, tracks due dates, and maintains accurate records of business obligations.

    Strong accounts payable management helps:

    • Avoid late fees
    • Maintain positive vendor relationships
    • Improve cash flow planning
    • Prevent duplicate payments

    When expenses are organized, your business operates more efficiently.


    5. Prepare Accurate Financial Reports

    One of the most valuable responsibilities of a bookkeeper is transforming financial transactions into reports that business owners can actually use.

    Each month, your bookkeeper prepares reports such as:

    • Profit & Loss Statement
    • Balance Sheet
    • Cash Flow Statement

    These reports provide insight into your company’s financial performance and become powerful tools for making informed business decisions.

    Why Bookkeeping Is Important

    Imagine trying to build a house without a blueprint.

    The workers might be busy every day, materials might be delivered on time, and progress may appear to be happening—but without a clear plan, mistakes become inevitable.

    Running a business without accurate bookkeeping is very similar.

    Many business owners judge the health of their company by checking their bank balance.

    While your bank account is certainly important, it only tells you how much cash you have today. It doesn’t tell you:

    • Whether your business is actually profitable.
    • Which services generate the highest margins.
    • Whether expenses are increasing too quickly.
    • Whether customers are paying on time.
    • Whether you can afford to hire another employee.
    • Whether your pricing is covering your true costs.

    Bookkeeping provides answers to these questions by transforming everyday transactions into meaningful financial information.

    Instead of making decisions based on intuition, you make decisions based on facts.

    Better Decisions Start with Better Information

    Every business owner makes financial decisions almost every day.

    Should you:

    • Purchase another service vehicle?
    • Hire an additional technician?
    • Increase employee wages?
    • Expand into another city?
    • Invest in new equipment?
    • Raise your prices?

    Without reliable financial information, these decisions become educated guesses.

    Professional bookkeeping gives you the confidence to make those decisions because your financial reports accurately reflect the current state of your business.

    The clearer your books become, the clearer your decisions become.

    That’s exactly why our tagline is:

    Accurate Books. Clear Decisions. Peace of Mind.

    Bookkeeping Helps You Understand Cash Flow

    One of the most common questions business owners ask is:

    “If we’re making money, why does it feel like we’re always short on cash?”

    The answer often comes down to cash flow.

    Profit and cash are not the same thing.

    For example:

    You may complete a $15,000 HVAC installation today.

    Your Profit & Loss Statement records that sale.

    However, if the customer doesn’t pay for another 30 days, that money isn’t available in your bank account today.

    Meanwhile, you still need to pay:

    • Employees
    • Fuel
    • Parts suppliers
    • Insurance
    • Rent
    • Payroll taxes

    Good bookkeeping helps business owners understand these timing differences before they become cash flow problems.

    Bookkeeping Makes Tax Season Easier

    For many small business owners, tax season feels overwhelming.

    Receipts are missing.

    Expenses need to be categorized.

    Bank statements have to be located.

    Questions arise about deductible expenses.

    When bookkeeping is maintained consistently throughout the year, tax preparation becomes much simpler.

    Instead of spending weeks gathering information, your records are already organized and ready for your CPA or tax professional.

    Good bookkeeping doesn’t replace your accountant—it makes your accountant’s job easier.

    Bookkeeping Supports Business Growth

    Growth creates complexity.

    As your business grows, so do:

    • Customer invoices
    • Vendor bills
    • Payroll
    • Equipment purchases
    • Bank transactions
    • Credit card expenses

    What once took an hour each month can eventually require several hours each week.

    Professional bookkeeping grows alongside your business, ensuring your financial systems remain organized even as your operations expand.

    That allows you to focus on growth instead of paperwork.

    Bookkeeping vs. Accounting

    Many people use the terms bookkeeping and accounting interchangeably.

    Although they work closely together, they serve different purposes.

    Understanding the distinction helps business owners know who they need and when.

    What Is Bookkeeping?

    Bookkeeping focuses on recording and organizing financial information.

    Think of bookkeeping as building the foundation of your financial records.

    Typical bookkeeping responsibilities include:

    • Recording daily transactions
    • Categorizing income and expenses
    • Reconciling bank and credit card accounts
    • Managing accounts receivable
    • Managing accounts payable
    • Preparing monthly financial reports
    • Maintaining organized financial records

    A professional bookkeeper ensures your financial data is complete and accurate.

    What Is Accounting?

    Accounting uses the financial information created through bookkeeping to help business owners make strategic decisions.

    Accountants often focus on:

    • Tax planning
    • Financial analysis
    • Budgeting
    • Forecasting
    • Business strategy
    • Tax return preparation
    • Financial consulting

    In simple terms:

    Bookkeeping records what happened.

    Accounting explains what it means.

    Both are essential—but accurate accounting begins with accurate bookkeeping.

    Think of It Like Building a Home

    Imagine you’re building a new home.

    The bookkeeper pours the foundation, frames the structure, and ensures everything is built correctly.

    The accountant helps design the finished home, recommends improvements, and plans for future expansion.

    Without a solid foundation, even the best design will eventually have problems.

    That’s why bookkeeping comes first.

    Five Signs It’s Time to Hire a Bookkeeper

    Many business owners wait too long before seeking bookkeeping help.

    Here are five common signs that it’s time to consider hiring a professional.

    1. You’re Spending More Time on Bookkeeping Than Running Your Business

    You started your business because you’re skilled at what you do—not because you enjoy reconciling bank accounts or categorizing expenses.

    If bookkeeping is consuming evenings, weekends, or valuable work hours, it may be time to delegate it to a professional.

    Your time is better spent serving customers, developing your team, and growing your business.

    2. Your Books Are Always Behind

    If you’re months behind on recording transactions, you’re making business decisions using outdated information.

    Current books lead to current insights.

    Outdated books lead to uncertainty.

    3. Your Financial Reports Don’t Make Sense

    Have you ever looked at your Profit & Loss Statement and wondered:

    “That can’t be right.”

    If your reports seem confusing or inaccurate, the underlying bookkeeping likely needs attention.

    Reliable reports begin with reliable bookkeeping.

    4. Tax Season Becomes a Source of Stress Every Year

    If every tax season involves searching for receipts, correcting mistakes, and scrambling to organize records, professional bookkeeping can dramatically reduce that stress.

    Consistent bookkeeping throughout the year means fewer surprises when it’s time to file taxes.

    5. You’re Growing Faster Than Your Financial Systems

    Growth is exciting—but it also creates more financial complexity.

    More employees.

    More invoices.

    More expenses.

    More transactions.

    More decisions.

    Eventually, DIY bookkeeping can no longer keep pace with your business.

    Professional bookkeeping provides the structure needed to support sustainable growth.

    A Real-World Example for an HVAC Business

    Imagine an HVAC company that completes 80 service calls each month.

    Every week, the business receives payments, purchases parts, pays technicians, fuels service vehicles, and manages dozens of vendor invoices.

    Without organized bookkeeping:

    • Customer payments may not be matched to invoices.
    • Vendor bills may be paid late.
    • Bank accounts may not reconcile correctly.
    • Profitability becomes difficult to measure.
    • Cash flow problems can go unnoticed until they become serious.

    With professional bookkeeping, every transaction is organized, every report is current, and the owner has a clear view of the business’s financial health.

    Instead of wondering where the money went, they know exactly how the business is performing—and they can make confident decisions about hiring, pricing, expansion, and investments..

    Perfect. This final section is arguably the most important.

    Many business blogs lose readers by ending abruptly or turning into a hard sales pitch. We won’t do that.

    Our goal is to educate first, build trust second, and invite the reader to take the next step naturally.

    This final section is designed to leave readers thinking:

    “Prime Ledger understands my business. They’re the kind of company I’d trust with my books.”

    How Prime Ledger Can Help

    Running a successful business already demands your attention in countless ways.

    You’re serving customers, managing employees, scheduling jobs, purchasing materials, handling unexpected issues, and planning for future growth.

    Bookkeeping shouldn’t be another source of stress.

    At Prime Ledger Bookkeeping, we help HVAC and service-based businesses keep their financial records accurate, organized, and up to date—so business owners can spend more time growing their business and less time worrying about their books.

    Our monthly bookkeeping services include:

    ✓ Monthly Bookkeeping

    We accurately record and organize your financial transactions, so your books remain current throughout the year.

    ✓ Bank & Credit Card Reconciliations

    We verify that your accounting records match your bank and credit card statements, helping identify errors before they become costly problems.

    ✓ Accounts Receivable Management

    We help you keep track of customer invoices and outstanding balances so you can improve cash flow and reduce overdue payments.

    ✓ Accounts Payable Management

    We organize vendor bills, monitor due dates, and help ensure your suppliers are paid accurately and on time.

    ✓ Monthly Financial Reports

    Receive clear, easy-to-understand financial reports that help you make informed business decisions with confidence.

    ✓ QuickBooks Online Support

    Whether you’re already using QuickBooks Online or planning to switch, we help ensure your bookkeeping system is organized and working effectively.

    More Than Bookkeeping

    Our goal isn’t simply to record transactions.

    Our goal is to provide business owners with financial clarity.

    When your books are accurate:

    • You understand your cash flow.
    • You know which services are most profitable.
    • You make decisions with greater confidence.
    • You prepare for tax season with less stress.
    • You spend more time growing your business.

    That’s the difference professional bookkeeping can make.

    Why Service-Based Businesses Choose Prime Ledger

    Service businesses operate differently than many other industries.

    They often manage:

    • Multiple jobs each day
    • Field technicians
    • Service vehicles
    • Parts inventory
    • Vendor relationships
    • Seasonal fluctuations
    • Customer invoices
    • Recurring operating expenses

    These moving parts create unique bookkeeping challenges.

    That’s why we focus on helping HVAC and other service-based businesses establish organized financial systems that support long-term growth.

    Whether you’re running a growing HVAC company, plumbing business, electrical contractor, landscaping service, cleaning company, or another service business, our goal is to help you gain greater confidence in your financial decisions.

    Key Takeaways

    If you remember only a few things from this guide, let them be these:

    ✅ Bookkeeping is much more than recording numbers—it creates the financial foundation of your business.

    ✅ Accurate bookkeeping helps you understand your cash flow, profitability, and overall financial health.

    ✅ Professional bookkeeping provides reliable financial reports that support smarter business decisions.

    ✅ Organized books reduce stress during tax season and make it easier to work with your accountant or CPA.

    ✅ As your business grows, professional bookkeeping becomes an investment in efficiency, accuracy, and long-term success.

    Frequently Asked Questions

    What does a bookkeeper do every day?

    A professional bookkeeper records financial transactions, categorizes income and expenses, reconciles bank accounts, tracks invoices and bills, maintains organized financial records, and prepares financial reports that help business owners understand how their business is performing.

    Is bookkeeping necessary for a small business?

    Yes.

    Even small businesses benefit from accurate bookkeeping because it helps owners monitor profitability, manage cash flow, prepare for tax season, and make informed financial decisions.

    The earlier good bookkeeping habits are established, the easier it becomes to grow the business successfully.

    What’s the difference between bookkeeping and accounting?

    Bookkeeping focuses on recording and organizing financial information.

    Accounting uses that information to analyze performance, prepare tax returns, develop budgets, and provide strategic financial guidance.

    Bookkeeping creates the foundation that accounting depends on.

    How often should bookkeeping be updated?

    Ideally, bookkeeping should be maintained consistently throughout the month.

    Waiting until the end of the year often creates unnecessary stress, increases the risk of errors, and makes it harder to understand your business’s financial position.

    Monthly bookkeeping keeps your financial information current and useful.

    Can I do my own bookkeeping?

    Many business owners handle their own bookkeeping when starting out.

    However, as a business grows and financial transactions become more complex, professional bookkeeping often saves significant time while improving accuracy and providing more reliable financial reporting.

    Why is accurate bookkeeping important for HVAC and service businesses?

    HVAC and service businesses often manage numerous invoices, vendor bills, payroll expenses, service vehicles, and customer payments every month.

    Accurate bookkeeping helps owners understand job profitability, improve cash flow, and make informed decisions that support business growth

    Conclusion

    Bookkeeping isn’t just an administrative task.

    It’s one of the most important financial systems your business relies on.

    When your financial records are accurate and organized, you gain more than compliance—you gain confidence.

    You understand your numbers.

    You identify opportunities sooner.

    You make better business decisions.

    You reduce unnecessary stress.

    And you create a stronger foundation for long-term growth.

    Whether your business is just getting started or has been serving customers for years, investing in professional bookkeeping is an investment in your company’s future.

    Remember:

    Better books lead to better decisions.

    And better decisions build stronger businesses.

    Ready to Gain Clarity in Your Business Finances?

    If you’re spending too much time managing your books—or simply want greater confidence in your financial information—we’re here to help.

    At Prime Ledger Bookkeeping, we specialize in helping HVAC and service-based businesses maintain accurate books, understand their financial performance, and focus on what they do best: serving their customers.

    Schedule your FREE Bookkeeping Consultation today and discover how professional bookkeeping can help your business grow with confidence.

    Prime Ledger Bookkeeping

    Accurate Books. Clear Decisions. Peace of Mind.