Your Bank Says One Number. Your Books Say Another.
You check your business bank account.
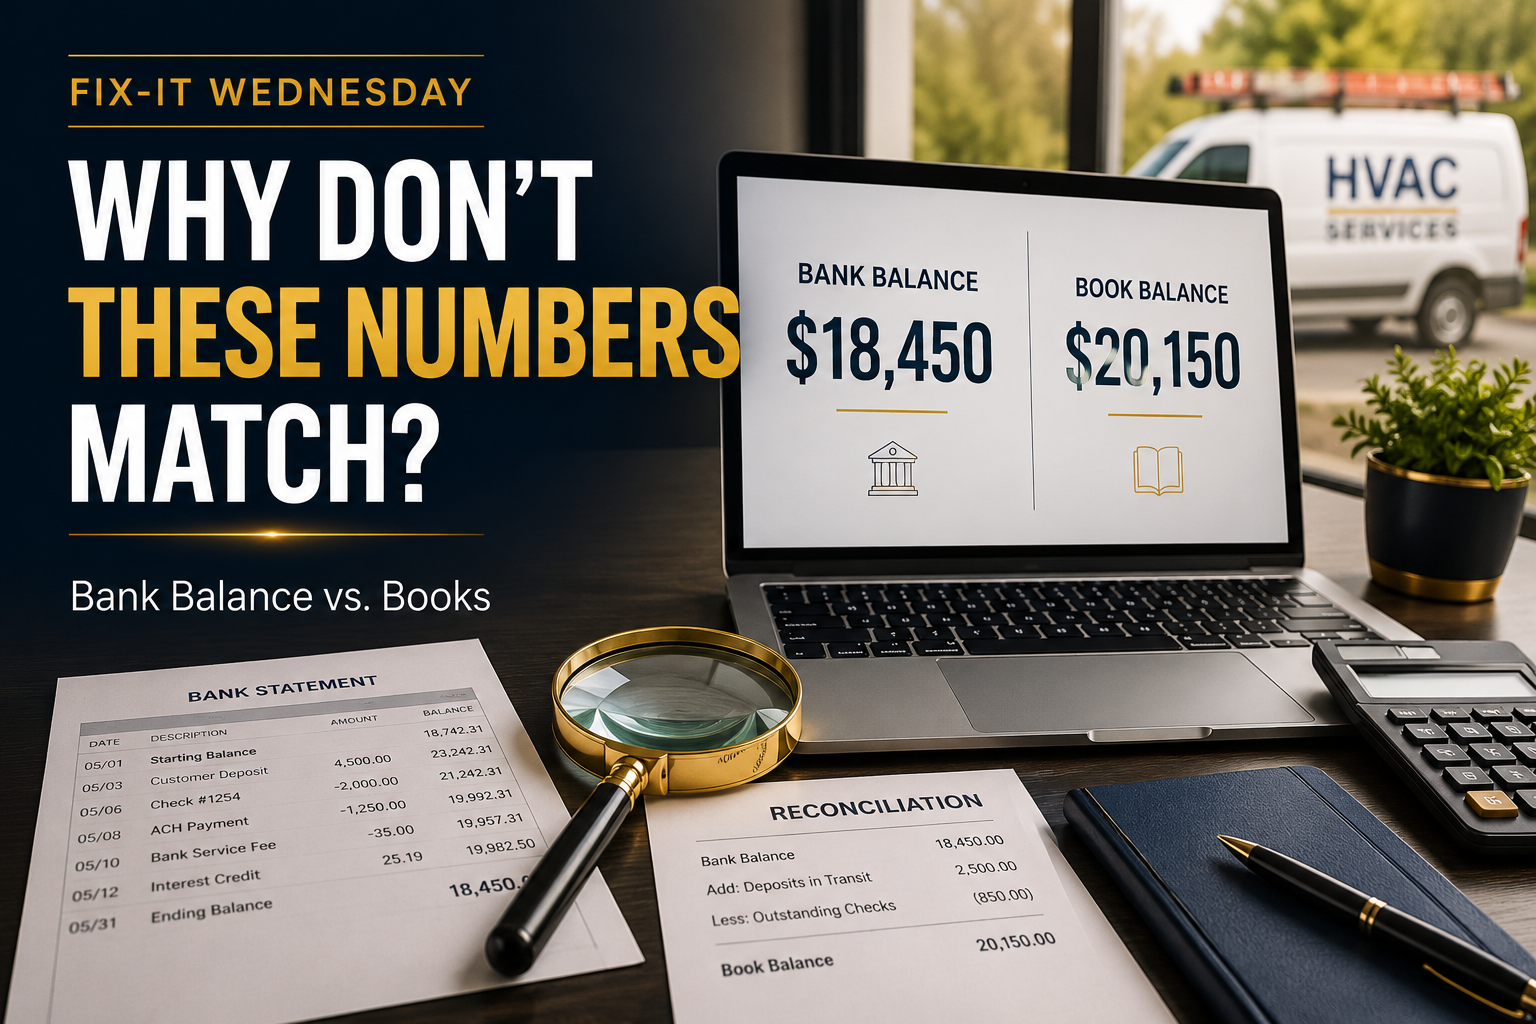
The balance says $18,450.
Then you open your accounting software.
The balance says $20,150.
And you immediately wonder:
“Which number is wrong?”
When your bank balance doesn’t match books, it’s easy to wonder which number is wrong.
For many small-business owners, seeing two different numbers can be alarming.
But here’s the good news:
A difference doesn’t automatically mean your bookkeeping is wrong.
Sometimes the difference is simply caused by timing.
A check may have been recorded in your books but hasn’t cleared the bank yet.
A deposit may have been recorded but hasn’t reached the bank account.
A bank fee may have appeared on your statement before it was entered into your accounting system.
Other times, however, the difference really does indicate a bookkeeping problem.
The key is knowing why the numbers don’t match.
In this guide, we’ll walk through seven common reasons your bank balance and books may be different, how to investigate the difference, and what you should avoid doing when trying to reconcile your accounts.
Table of Contents
- Should Your Bank Balance and Books Match?
- The 7 Common Reasons Your Balances Don’t Match
- How to Find the Difference
- Don’t Just Force the Reconciliation
- An HVAC Business Example
- When a Difference Is a Red Flag
- How to Prevent Reconciliation Problems
- When to Get Professional Bookkeeping Help
- How Prime Ledger Can Help
- Key Takeaways
- Frequently Asked Questions
- Conclusion
Should Your Bank Balance and Books Match?
This is the first thing to understand.
Your bank balance and your book balance don’t necessarily have to be identical at every moment.
There can be legitimate differences between the two.
For example, you may write a check today and record it in your accounting system.
Your books immediately reflect the payment.
But the recipient may not deposit the check for several days.
Until the bank processes it, your bank balance won’t reflect the withdrawal.
That’s a timing difference.
The same thing can happen with deposits.
You might record a customer payment in your books on Friday, but the bank may not credit the account until Monday.
So when your bank balance doesn’t match your books, the first question isn’t:
“Which number is wrong?”
It’s:
“Can I explain the difference?”
If you can explain it through legitimate timing differences or known transactions that haven’t yet been recorded, that’s very different from an unexplained discrepancy.
The 7 Common Reasons Your Balances Don’t Match
1. Outstanding Checks
An outstanding check is a payment that has been recorded in your books but hasn’t cleared the bank yet.
For example:
You issue a $2,000 check to a vendor on August 10.
You record the payment in your books that day.
Your book balance decreases by $2,000.
But the vendor doesn’t deposit the check until August 15.
Until the check clears, your bank statement won’t reflect that $2,000 withdrawal.
What happens?
Books: Payment recorded
Bank: Payment not yet cleared
That’s a normal timing difference.
It doesn’t necessarily mean anything is wrong.
2. Deposits in Transit
Deposits in transit are essentially the opposite situation.
You may have recorded a deposit in your books, but the bank hasn’t processed it yet.
Imagine an HVAC customer pays a $4,500 invoice on Friday.
You record the payment and deposit in your accounting system.
But the funds don’t appear in the bank until Monday.
Your books show the additional $4,500.
Your bank doesn’t yet.
Again, this can be a normal timing difference.
3. Bank Fees Were Not Recorded
Sometimes the bank balance is lower than the balance in your books because the bank has charged a fee that hasn’t been recorded in your accounting system.
Examples could include:
- Monthly service fees
- Wire fees
- Transaction fees
- Stop-payment fees
- Other bank charges
Suppose your bank deducts a $35 service fee.
Your bank balance decreases immediately.
But if you haven’t entered the $35 expense into your books, your accounting balance won’t reflect it.
Now you have a difference that needs to be recorded and reconciled.
4. Interest or Other Bank Credits Were Missed
The difference can also work in the opposite direction.
Your bank may add:
- Interest income
- Refunds
- Credits
- Other adjustments
If those amounts haven’t been recorded in your accounting system, your bank balance may be higher than your book balance.
For example, if your bank adds $25 of interest but your books don’t include it, you’ll have a $25 difference to investigate.
The solution isn’t complicated in principle:
Identify the transaction, record it appropriately, and reconcile the account.
5. Duplicate or Missing Transactions
Now we’re getting into actual bookkeeping errors.
A transaction may have been:
- Entered twice
- Never entered
- Recorded for the wrong amount
- Recorded on the wrong date
Imagine your business purchased $600 of equipment.
The transaction accidentally gets entered twice.
Your books now show a $1,200 expense.
The bank only shows the actual $600 payment.
Your balances won’t reconcile because the books contain an extra transaction.
The same problem can happen when a transaction is missing completely.
6. A Transaction Was Recorded in the Wrong Account
This can become particularly confusing when a business has multiple bank accounts.
Suppose your company has:
- Operating checking
- Payroll checking
- Savings
- Business credit card
A $1,000 payment actually came out of your operating account.
But it was mistakenly recorded against the payroll account.
The transaction exists in your books.
The amount may even be correct.
But it’s associated with the wrong account.
As a result, one account may appear too high while another appears too low.
This is one reason it’s important to review which account a transaction was posted to, not just whether the transaction exists.
7. A Previous Reconciliation Was Incorrect
Sometimes today’s problem started months ago.
A previous reconciliation may have been completed incorrectly.
Perhaps:
- A transaction was accidentally deleted.
- A reconciled transaction was changed.
- A duplicate transaction was created.
- An opening balance was altered.
- An adjustment was entered incorrectly.
If the prior reconciliation was wrong, the current reconciliation may continue to show a difference.
This is why unexplained reconciliation discrepancies can sometimes require looking backward rather than only reviewing the current month.
How to Find the Difference
So what should you actually do when your bank balance doesn’t match books?
Don’t start by changing random transactions.
Instead, work through the problem systematically.
Step 1: Confirm the Correct Bank Statement
Make sure you’re comparing the correct:
- Bank account
- Statement period
- Statement ending date
- Statement ending balance
It sounds obvious, but using the wrong statement period can make a reconciliation impossible.
Step 2: Compare the Ending Balance
Look at the ending balance shown on your bank statement.
Then compare it with the corresponding balance in your accounting system.
Determine exactly how much the difference is.
For example:
Bank: $18,450
Books: $20,150
Difference: $1,700
Now you have a specific number to investigate.
Step 3: Look for Outstanding Transactions
Review transactions that have been recorded in your books but haven’t cleared the bank.
These may include:
- Outstanding checks
- Recent electronic payments
- Deposits in transit
Timing differences may explain part or all of the discrepancy.
Step 4: Review Bank Charges and Credits
Look carefully at your bank statement.
Check for transactions that aren’t currently recorded in your books.
Look for:
- Service fees
- Interest
- Bank charges
- Refunds
- Other credits or adjustments
These are often easy to overlook.
Step 5: Look for Duplicates
Review your accounting records for duplicate entries.
Pay particular attention to:
- Large transactions
- Recently imported transactions
- Manually entered transactions
- Transactions entered both manually and through a bank feed
A duplicate transaction can create a difference even though the original transaction is correct.
Step 6: Look for Missing Transactions
Now work in the opposite direction.
Is there something on the bank statement that isn’t in your books?
Go through the statement and compare it with the accounting records.
Pay attention to:
- Checks
- Deposits
- Electronic payments
- Bank fees
- Transfers
- Interest
Step 7: Check the Account
If the transaction exists but the balance still doesn’t make sense, verify that it was recorded in the correct bank account.
This becomes especially important when the business has multiple accounts.
Step 8: Review Previous Reconciliations
If you still can’t explain the difference, don’t assume the current month is the problem.
Review earlier reconciliations.
A previous error can carry forward into subsequent periods.
Don’t Just Force the Reconciliation
This deserves its own section because it’s one of the most important lessons in this article.
When your accounting software shows a reconciliation difference, it can be tempting to make an adjustment just to get the numbers to zero.
But zero isn’t the goal.
Accuracy is the goal.
If you enter a random adjustment simply to make the reconciliation balance, you may hide the real problem.
The books might appear reconciled, but the underlying financial information could still be incorrect.
That can create additional problems later when you’re reviewing:
- Profitability
- Cash flow
- Financial statements
- Tax information
- Accounts receivable
- Accounts payable
If you don’t understand why the difference exists, investigate it before making an adjustment.
An HVAC Business Example
Let’s look at a realistic example.
Imagine an HVAC company has a bank balance of $25,000.
Its accounting system shows $27,500.
At first, the owner is concerned.
But the bookkeeper reviews the transactions and finds:
$2,000 outstanding vendor check
The check was recorded in the books but hasn’t cleared the bank.
And:
$500 deposit in transit
A customer payment was recorded but hasn’t reached the bank yet.
Now the difference is understandable.
The two balances aren’t identical because of timing.
That is very different from discovering that:
- A $500 payment was recorded twice
- A $1,000 bank fee was never recorded
- A $750 transaction was posted to the wrong bank account
Those are bookkeeping issues that need to be corrected.
The important point is:
Don’t assume every difference is an error—but don’t ignore unexplained differences either.
When a Difference Is a Red Flag
A difference deserves closer attention when:
The amount is significant.
A small timing difference may be normal.
A large unexplained difference deserves investigation.
The difference has no clear explanation.
If you can’t identify why the balances differ, don’t simply move on.
The discrepancy keeps appearing.
If you’re constantly carrying unexplained differences from month to month, your reconciliation process may need attention.
Previous reconciliations were changed.
Changes to previously reconciled transactions can create problems that aren’t immediately obvious.
Your books haven’t been reconciled regularly.
The longer you go without reconciliation, the harder it can become to identify when the problem started.
Multiple accounts are affected.
If money is moving between several bank accounts and the balances don’t make sense, the issue may be more complicated than a simple timing difference.
How to Prevent Reconciliation Problems
The best reconciliation problem is the one you don’t have to fix later.
A consistent monthly bookkeeping process can help.
Reconcile Your Accounts Regularly
Don’t wait several months before comparing your books with your bank statements.
Regular reconciliation makes discrepancies easier to identify while the transactions are still fresh.
Keep Business and Personal Transactions Separate
Mixing personal and business activity can make your financial records much more difficult to maintain and reconcile.
Keeping business activity in dedicated business accounts can simplify the bookkeeping process.
Review Your Books Before Closing the Month
Look for unusual transactions, duplicate entries, missing transactions, and unexplained balances before considering the month complete.
Don’t Ignore Small Differences
A $10 difference may not seem important.
But if you repeatedly ignore small discrepancies, they can become much harder to trace later.
The goal isn’t to obsess over every cent.
It’s to establish a process that makes unexplained differences visible and manageable.
When to Get Professional Bookkeeping Help
If you’re comfortable working through simple reconciliation differences, you may be able to resolve many issues yourself.
But professional help may make sense when:
- You have several months of unreconciled accounts.
- Your books don’t balance consistently.
- You have multiple bank and credit card accounts.
- Previous reconciliations contain errors.
- Transactions have been deleted or changed after reconciliation.
- You have a large number of unexplained transactions.
- You aren’t confident in the accuracy of your financial reports.
The longer a bookkeeping problem remains unresolved, the more difficult it can become to determine where it started.
Getting help early can sometimes save considerable time and cleanup work later.
How Prime Ledger Can Help
At Prime Ledger Bookkeeping, we help HVAC and service-based businesses keep their financial records organized, reconciled, and current.
Our services include:
- Monthly bookkeeping
- Bank and credit card reconciliations
- Accounts receivable
- Accounts payable
- Bookkeeping cleanup and catch-up
- Financial reporting
- QuickBooks Online support
We don’t believe reconciliation is simply about making two numbers match.
It’s about making sure the financial records behind those numbers are accurate.
Because when you can trust your books, you can make better decisions about your business.
Accurate Books. Clear Decisions. Peace of Mind.
🔧 Key Takeaways
If your bank balance doesn’t match your books, don’t panic—and don’t immediately force the reconciliation.
Remember:
✅ Not every difference is an error. Timing differences can occur because of outstanding checks and deposits in transit.
✅ Some differences require correction. Missing transactions, duplicate entries, bank fees, and incorrectly posted transactions can create real discrepancies.
✅ Find the reason before making an adjustment. Making a random adjustment just to reach zero can hide an underlying problem.
✅ Review previous reconciliations if the current difference can’t be explained.
✅ Reconcile regularly to catch problems while they’re still easy to investigate.
Most importantly:
A reconciled account should be accurate—not simply made to balance.
Frequently Asked Questions
Why doesn’t my bank balance match my books?
Your bank balance may differ from your book balance because of timing differences, such as outstanding checks or deposits in transit, or because of bookkeeping issues such as missing, duplicate, or incorrectly recorded transactions.
Should my bank balance and book balance always match?
Not necessarily. Legitimate timing differences can cause the balances to differ temporarily. The important thing is that the difference can be explained and properly accounted for during reconciliation.
Why doesn’t my bank balance match QuickBooks?
Common reasons include outstanding transactions, deposits that haven’t cleared, bank fees that haven’t been recorded, duplicate or missing transactions, transactions posted to the wrong account, or errors from previous reconciliations.
What is a bank reconciliation?
A bank reconciliation is the process of comparing the transactions and balance in your accounting records with the information on your bank statement and identifying differences that need to be explained or corrected.
What are outstanding checks?
Outstanding checks are checks that have been recorded in your books but have not yet cleared your bank account. They can create a temporary difference between the bank balance and book balance.
What are deposits in transit?
Deposits in transit are deposits recorded in your books that have not yet been processed or credited by the bank. They can create a temporary difference during reconciliation.
How do I fix a bank reconciliation discrepancy?
Start by confirming the correct account and statement period, then compare the ending balances and review outstanding transactions, deposits, bank fees, missing or duplicate transactions, and account assignments. If the difference remains unexplained, review previous reconciliations or seek professional bookkeeping assistance.
Should I force QuickBooks to reconcile?
No. You should generally identify and understand the reason for a reconciliation difference rather than making an arbitrary adjustment simply to force the account to balance. An unexplained adjustment can hide an underlying bookkeeping error.
Conclusion
Seeing your bank balance and books show different numbers can be unsettling.
But a difference doesn’t automatically mean something is wrong.
Sometimes the explanation is simple:
A check hasn’t cleared.
A deposit is still in transit.
A bank fee hasn’t been recorded yet.
Other times, the difference points to a genuine bookkeeping problem.
The important thing is to understand the difference instead of simply making it disappear.
When your bank balance doesn’t match your books, work through the reconciliation systematically. Check for timing differences, missing transactions, duplicates, bank charges, incorrect account assignments, and previous reconciliation issues.
And if you can’t determine why the numbers don’t match, don’t be afraid to get professional help.
Because the goal of bookkeeping isn’t simply to make the numbers balance.
The goal is to make sure the numbers are accurate enough to trust.
And when you can trust your books, you can make business decisions with greater confidence.
🔧 Can’t Figure Out Why Your Numbers Don’t Match?
If your bank balance and books don’t match—and you can’t determine why—Prime Ledger Bookkeeping can help.
We help HVAC and service-based businesses with bank reconciliations, bookkeeping cleanup, monthly bookkeeping, accounts receivable, accounts payable, and financial reporting.
Schedule a free bookkeeping consultation.
Let’s identify what’s happening with your books and help you get your financial records back on track.
Accurate Books. Clear Decisions. Peace of Mind.
Related Articles
📚 Bookkeeping Basics Monday
What Does a Bookkeeper Do? A Complete Guide for Small Business Owners
Learn what a professional bookkeeper does, including how regular reconciliations help keep financial records accurate.
Bookkeeping vs. Accounting Explained
Understand where bookkeeping fits within your broader financial system and how it works alongside accounting.
🔧 Fix-It Wednesday
Your Books Are Months Behind—Now What?
If your reconciliations haven’t been done in months, start here with our practical catch-up bookkeeping guide.
📈 Finance Friday
5 Signs It’s Time to Hire a Bookkeeper
Recurring reconciliation problems may be one sign that your business has outgrown DIY bookkeeping.
Leave a Reply